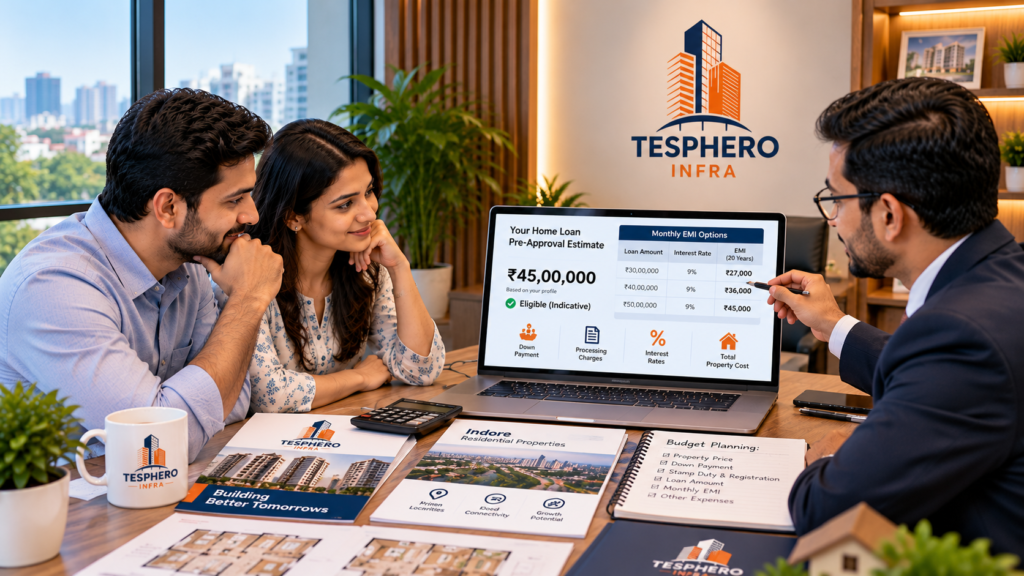
Tesphero Infra helps home buyers in Indore understand home loan pre-approval, monthly EMI estimates, down payment requirements, and overall property costs before making a buying decision.
Home Loan Pre-Approval helps buyers understand their potential borrowing capacity before they start searching for a property. Many people begin their home-buying journey by visiting apartments, comparing locations, and exploring attractive projects. However, they often overlook an important question: How much property can they comfortably afford?
Imagine finding a beautiful apartment in Indore that matches your family’s requirements. The location is convenient, the rooms are spacious, and the price appears reasonable. However, when you approach a lender, you discover that your eligible loan amount may be lower than expected.
As a result, you may need to reconsider the property or arrange additional funds.
Understanding your finances before property hunting can help you avoid such situations.
A preliminary loan assessment may provide an estimate of your borrowing eligibility. More importantly, it encourages you to review your income, existing EMIs, savings, and future expenses before making a major financial commitment.
However, pre-approval does not guarantee final loan sanction. Lenders may still need to verify your documents, assess the property, and complete additional checks.
This guide explains how the process works, why it matters, and how buyers in Indore can plan their property budget more effectively.
Table of Contents
- What Is Home Loan Pre-Approval?
- Why Your Property Budget Matters
- Pre-Approval vs Final Loan Sanction
- How Much Property Can You Afford?
- What Do Lenders Check?
- Seven Benefits of Home Loan Pre-Approval
- Common Mistakes to Avoid
- Property Buying in Indore
- How to Prepare Before Applying
- What to Check After Selecting a Property
- How Tesphero Infra Can Help
- Frequently Asked Questions
1. What Is Home Loan Pre-Approval?
Home loan pre-approval is a preliminary assessment of a borrower’s financial eligibility.
A bank or housing finance company may review income, employment details, existing loans, credit history, and other relevant information to estimate how much the applicant could potentially borrow.
For example, a buyer may expect to qualify for a ₹50 lakh loan. However, after reviewing existing financial commitments, a lender might indicate a lower amount.
This information can help the buyer adjust their property search before making significant commitments.
How Does It Work?
The process generally involves submitting financial information, completing the lender’s initial checks, and receiving an indicative eligibility assessment.
However, different lenders may use terms such as pre-qualification, in-principle approval, and pre-approval differently.
Therefore, ask what the assessment includes and whether any conditions remain.
Remember: A preliminary approval does not mean the selected property has passed legal or technical verification.
2. Why Your Property Budget Matters
A property’s advertised price is only one part of the buying cost.
Depending on the transaction, buyers may also need funds for stamp duty, registration, applicable taxes, loan-related charges, brokerage, moving expenses, and basic furnishing.
Therefore, your available savings should not automatically be treated as the entire down payment.
Understand the Total Purchase Cost
Suppose a buyer has ₹12 lakh in savings and plans to purchase a property.
Using the full amount as a down payment could leave little money for registration expenses, repairs, or emergencies.
Instead, the buyer should estimate all upfront costs before deciding how much to contribute.
Avoid Searching Beyond Your Budget
Imagine a family starts visiting homes priced between ₹65 lakh and ₹75 lakh.
After several visits, they shortlist a property they love. However, their income and existing obligations may support a smaller loan than expected.
Consequently, they may need to abandon the purchase or stretch their finances.
A clear budget helps buyers focus on suitable properties from the beginning.
For additional guidance, read our previous blog:
What Makes a Property Location Valuable? 7 Factors Buyers Should Consider
Factors that make a property location valuable
3. Home Loan Pre-Approval vs Final Loan Sanction
These two stages serve different purposes.
| Factor | Pre-Approval | Final Loan Sanction |
|---|---|---|
| Purpose | Preliminary borrowing assessment | Formal lending decision |
| Financial review | Initial or conditional checks | More complete verification |
| Property details | May not be required initially | Generally required |
| Legal and technical checks | Usually not completed for a specific property | Typically required |
| Loan amount | Indicative | Sanctioned subject to conditions |
| Disbursement | Not guaranteed | Subject to fulfilment of disbursement conditions |
For example, a buyer may receive an indicative eligibility amount of ₹40 lakh.
However, after selecting a property, the lender may review its valuation, ownership documents, and relevant approvals.
If the property does not meet the lender’s requirements, the application may face delays or rejection.
Therefore, financial eligibility and property eligibility are separate considerations.
This distinction is particularly important when comparing under-construction and ready-to-move homes.
Related blog:
Under-Construction vs Ready-to-Move Property: What Should Buyers Compare Before Choosing?
Compare under-construction and ready-to-move properties
4. How Much Property Can You Actually Afford?
The maximum loan amount a lender may offer is not necessarily the amount you should borrow.
A comfortable home-buying budget depends on your income, monthly expenses, savings, and future responsibilities.
Start With Your Monthly Finances
Consider this hypothetical example:
| Monthly Financial Details | Amount |
|---|---|
| Household take-home income | ₹90,000 |
| Essential expenses | ₹35,000 |
| Existing loan EMIs | ₹12,000 |
| Savings and other commitments | ₹15,000 |
| Remaining amount | ₹28,000 |
Although ₹28,000 remains after these expenses, using the entire amount for a home loan EMI may create financial pressure.
Unexpected medical expenses, school fees, repairs, or income changes can affect household finances.
Therefore, choose an EMI that leaves room for flexibility.
Understand the EMI Before Borrowing
The following calculations assume a 9% annual interest rate and a 20-year tenure.
| Loan Amount | Approximate Monthly EMI |
|---|---|
| ₹20 lakh | ₹18,000 |
| ₹30 lakh | ₹27,000 |
| ₹40 lakh | ₹36,000 |
| ₹50 lakh | ₹45,000 |
These figures are rounded illustrations, not current lender quotations. Actual EMIs depend on the offered rate, tenure, and loan conditions.
A higher loan amount generally increases the monthly installment. Meanwhile, extending the tenure may reduce the EMI but increase total interest.
Also, remember that lenders may not finance the entire property cost. The required buyer contribution depends on applicable rules, lender policies, and property valuation.
As a result, down payment planning is just as important as EMI planning.
5. What Do Lenders Check During Home Loan Pre-Approval?
Lenders assess several factors before indicating potential borrowing eligibility.
Income and Employment Stability
Regular, verifiable income helps lenders assess repayment capacity.
Salaried applicants may need to provide employment and salary records. Meanwhile, self-employed buyers may need business financial statements and income tax documents.
However, requirements vary between lenders.
Credit History
Lenders may review previous borrowing and repayment behaviour.
Missed payments or other credit-related concerns can influence the assessment.
Still, no particular credit score guarantees loan approval.
Existing Financial Obligations
Personal loans, vehicle loans, and other EMIs reduce the amount available for additional repayments.
For example, two applicants with similar incomes may receive different eligibility estimates if their existing debt commitments differ.
Age, Tenure and Savings
The applicant’s age, requested repayment period, and available contribution may also influence the assessment.
Some lenders may consider an eligible co-applicant’s income, subject to their policies.
Therefore, organize your financial details before approaching a lender.
For official banking information, refer to the Reserve Bank of India.
6. Seven Benefits of Home Loan Pre-Approval
Understanding your borrowing eligibility early can make the property search more focused.
1. Establish a Realistic Price Range
A preliminary assessment can help you identify a practical property budget.
Instead of viewing homes across many price categories, you can concentrate on options that match your financial plan.
2. Save Time During Property Hunting
Visiting properties beyond your budget can waste time and create disappointment.
However, a defined price range makes shortlisting easier.
You can compare relevant properties based on location, size, amenities, and condition.
3. Plan Your Down Payment
An eligibility estimate can help you understand the possible gap between the property price and available financing.
Therefore, you can plan your savings more carefully.
Remember that final financing may change after property valuation and other lender checks.
4. Identify Financial Concerns Early
Existing loans, incomplete documents, or credit-related issues may affect eligibility.
An early assessment can bring these concerns to your attention before you make a major property commitment.
5. Make Better Family Budget Decisions
Buying a home affects the entire household.
Understanding the expected EMI can help family members discuss education expenses, savings, and future responsibilities.
For example, choosing a slightly smaller apartment may allow a family to maintain a healthier financial reserve.
6. Compare Properties More Effectively
Once your budget is clearer, you can compare homes according to practical requirements.
A property with attractive interiors may not be the best choice if its purchase cost creates excessive financial pressure.
Therefore, affordability should remain part of every comparison.
7. Prepare for Property Negotiations
Knowing your financing position can help you discuss payment schedules and purchase conditions more confidently.
However, pre-approval does not guarantee that a seller will accept your offer or that the lender will approve the final transaction.
Its main value is better preparation.
7. Common Mistakes Home buyers Should Avoid
Even financially prepared buyers can make mistakes during the property search.
Choosing the Maximum Possible Loan
A lender’s estimated eligibility should not become your automatic borrowing target.
Instead, consider the EMI you can comfortably manage while maintaining essential savings.
Ignoring Additional Purchase Expenses
Stamp duty, registration, repairs, and moving expenses may increase the total cost.
Therefore, prepare a complete budget rather than focusing only on the advertised price.
Making a Large Booking Payment Too Early
Some buyers pay substantial booking amounts before confirming their financing options.
However, cancellation and refund conditions vary.
Read the booking agreement carefully before making financial commitments.
Assuming Pre-Approval Guarantees a Loan
A preliminary assessment may remain subject to document verification, updated financial checks, property valuation, and other conditions.
Therefore, do not treat it as a final sanction.
Ignoring Property Documentation
A financially eligible buyer may still face problems if the selected property has unresolved legal or approval-related issues.
Consequently, independent verification remains important.
8. How Home Loan Pre-Approval Helps Buyers in Indore
Property buyers in Indore may consider apartments, independent houses, or residential plots across different neighborhoods and developing areas.
However, prices and property characteristics can vary significantly.
Therefore, understanding your budget before selecting a location can make the search more practical.
An Example From a Buyer’s Perspective
Imagine a family comparing two apartments.
The first property is more affordable but requires a longer daily commute.
The second is closer to the workplace and school but has a higher purchase price.
Without financial clarity, the family may focus mainly on convenience.
However, after estimating the EMI, upfront expenses, and monthly savings, they can make a more balanced decision.
Consider Everyday Requirements
Along with affordability, evaluate road connectivity, nearby schools, healthcare access, water and electricity arrangements, maintenance costs, and property condition.
Also, avoid assuming that every developing location will deliver higher future appreciation.
Market conditions and infrastructure development can change.
A suitable home should fit both your lifestyle and your financial capacity.
9. How to Prepare Before Applying
You do not need to complete your entire property search before discussing financing with a lender.
Instead, prepare the essential information early.
Step 1: Review Your Income
Calculate regular household income using reliable figures.
If your earnings fluctuate, use a cautious estimate.
Step 2: List Existing Commitments
Include current EMIs, household expenses, education costs, insurance premiums, and other recurring payments.
This helps you understand your repayment capacity.
Step 3: Check Your Savings
Separate funds available for the purchase from money required for emergencies and other financial goals.
Step 4: Estimate a Comfortable EMI
Compare possible loan amounts, interest rates, and repayment tenures.
Consider both monthly affordability and total interest.
Step 5: Prepare Documents
Commonly requested documents may include identity proof, income records, bank statements, and details of existing loans.
Self-employed applicants may need additional business and tax records.
Step 6: Compare Lenders
Discuss eligibility with suitable banks or housing finance companies.
Ask about interest rate structures, applicable charges, preliminary approval conditions, and validity periods.
Step 7: Begin Property Shortlisting
Once your financial range is clearer, compare properties that match your budget and requirements.
This approach can reduce unnecessary visits and unrealistic expectations.
10. What Should Buyers Check After Selecting a Property?
Home Loan Pre-Approval is only one part of the buying process.
After shortlisting a property, buyers should complete appropriate legal, technical, and financial checks.
Verify Ownership and Documents
Review the relevant title and ownership records.
Depending on the transaction, additional documents and professional legal verification may be necessary.
For more guidance, read:
Property Buyers: 10 Essential Documents You Should Never Ignore
Important property documents buyers should verify
Check Applicable Approvals
For relevant real estate projects in Madhya Pradesh, verify applicable registration and project details through the MP RERA official website.
However, RERA registration does not replace other necessary legal or technical checks.
Understand the Payment Schedule
Review booking terms, payment milestones, and the sale agreement.
Also, check whether the proposed schedule is compatible with the lender’s disbursement conditions.
Confirm Final Loan Sanction
The lender may still assess the selected property’s valuation, legal status, and supporting documents.
Therefore, do not assume that preliminary eligibility guarantees funding for every property.
11. How Tesphero Infra Can Help
Buying property involves several connected decisions.
You need to understand your budget, choose a suitable location, compare available options, and review important documentation.
At Tesphero Infra, we believe buyers should begin with clear requirements and realistic financial expectations.
For example, a family looking for an apartment in Indore may have preferences regarding location, size, and amenities. However, the available budget can determine which properties deserve serious consideration.
Starting with financial clarity can make the search more focused.
Planning to Buy Property in Indore?
Tesphero Infra can help you explore property options according to your preferences and budget.
Whether you are considering an apartment, independent house, or residential plot, understanding your financial limits is an important starting point.
However, home loan eligibility, sanction, and disbursement remain subject to the lender’s decisions and conditions. Property-related legal and technical verification should also be completed through appropriate professionals.
Connect with Tesphero Infra to discuss your property requirements in Indore and begin your search with a clearer plan.
Conclusion
Home Loan Pre-Approval can help buyers understand their potential borrowing capacity before they begin serious property hunting.
It can help establish a realistic budget, identify financing concerns, and focus property comparisons.
However, preliminary eligibility is not the same as final loan sanction.
Buyers should still review their comfortable EMI, savings, down payment, transaction costs, and the selected property’s documentation.
For families planning to buy a home in Indore, early financial preparation can make the process more organized.
Ultimately, the right property is not simply the most expensive home you can finance. It meets your family’s needs without creating unnecessary financial pressure.
Frequently Asked Questions
About the Author
Tesphero Infra shares practical information on property buying, location selection, real estate documentation, and investment considerations, focusing on helping buyers make informed property decisions in Indore.
Disclaimer: This article is for general educational purposes and does not constitute personalized financial, legal, or lending advice. Loan eligibility, interest rates, documentation, sanction, and disbursement depend on lender policies and applicable rules. Buyers should verify property documents and obtain appropriate professional guidance before making commitments.
Tesphero Infra helps home buyers in Indore explore suitable properties, review floor plans, and evaluate location advantages to make informed decisions within their planned budget.