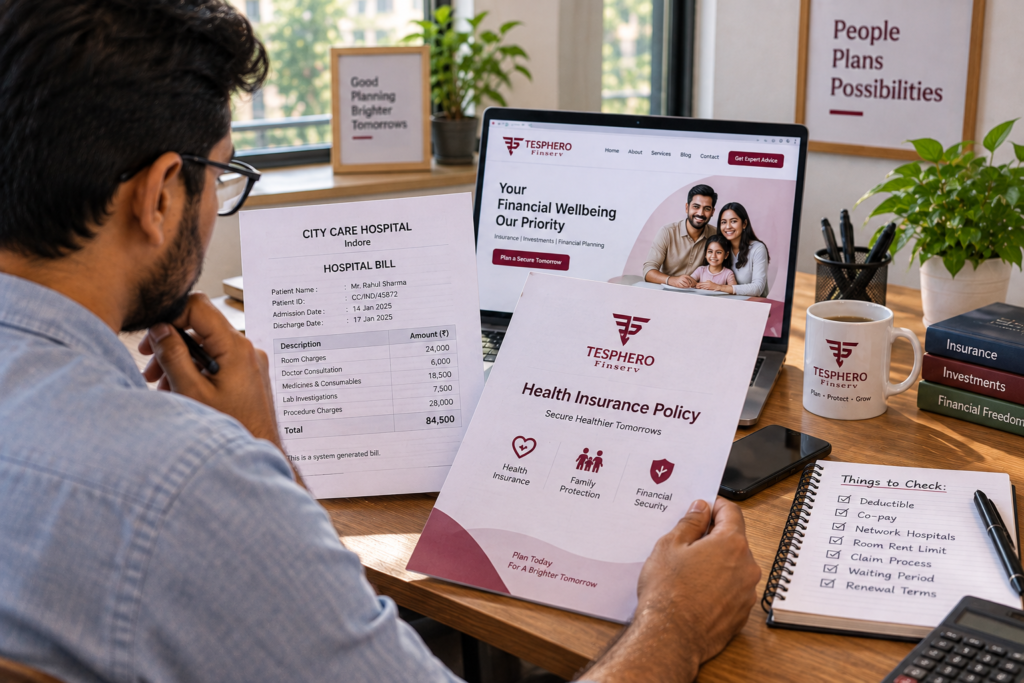
Reviewing a hospital bill alongside a health insurance policy to understand deductible terms.
A health insurance deductible is one of those terms that sounds simple but often confuses people only when a hospital bill actually arrives. Many people in India assume that once they buy a policy, every covered expense gets paid by the insurer. However, that is not always how it works. Depending on the policy, you may still need to pay a certain portion yourself before your insurer starts settling the rest.
This gap between what you expect and what you actually pay often comes down to a few key terms: deductible, premium, and copay. Each one plays a different role in deciding your final out-of-pocket cost.
This article breaks these terms down in plain language, using Indian examples and rupee figures. By the end, you should have a clearer sense of how a deductible works, how it differs from a copay, and what questions to ask before choosing a policy.
Table of Contents
- What Is a Health Insurance Deductible?
- How a Health Insurance Deductible Works
- Types of Deductibles in India
- Deductible vs Copay
- How Deductibles Affect Premiums and Costs
- How to Compare Health Insurance Plans
- Common Mistakes to Avoid
- How Tesphero Finserv Can Help
- Frequently Asked Questions
What Is a Health Insurance Deductible?
A health insurance deductible is the portion of an eligible medical expense that you agree to pay before your insurer contributes. In simple terms, it works like a threshold. Costs below this amount are usually paid by you. Costs above it may be settled by the insurance company, subject to the policy’s terms.
Here is a basic illustrative example. Suppose your hospital bill comes to ₹1,00,000, and your policy has an applicable deductible of ₹20,000. In this case, you would typically pay the first ₹20,000. The insurer may then settle the remaining ₹80,000, depending on other conditions in the policy.
This is only an example to explain the concept. Real policies vary widely, so the exact amount and application of a deductible depend entirely on your specific plan.
How Does a Health Insurance Deductible Work?
The process generally follows a few steps, though the exact mechanics differ across insurers.
- You receive treatment and generate a medical bill.
- The deductible amount, if applicable, is calculated first.
- You pay this portion from your own funds.
- The insurer processes the remaining eligible amount according to the policy terms.
Some deductibles apply per claim. Others may apply per policy year. Because of this, it is important to read your policy document carefully rather than assume how it functions.
Does Every Health Insurance Policy Have a Deductible?
Not every policy in India includes a deductible. Many standard indemnity health plans do not carry one at all. On the other hand, some products, particularly top-up and super top-up plans, are built around a deductible-like structure.
So, it is not accurate to assume that all policies work the same way. Instead, check your specific policy wording to confirm whether a deductible applies, and if so, how.
When Does a Deductible Apply?
This depends on the product type and the specific conditions set by the insurer. In some plans, a deductible applies to every claim. In others, it may apply only once a year, or only under certain product categories like top-up covers.
Because these conditions vary so much, avoid making blanket assumptions. Always confirm the details directly from your policy document or your insurer.
Types of Health Insurance Deductibles in India
Deductibles are not a single, fixed concept. A few different types exist, and understanding each one can help you read a policy brochure more confidently.
Compulsory Deductible
A compulsory deductible is a fixed amount set by the insurer as part of the policy structure. You cannot opt out of it. It typically applies automatically to eligible claims, and the exact figure is mentioned in the policy schedule.
Voluntary Deductible
A voluntary deductible works differently. Here, you choose to take on a higher share of an eligible expense yourself. In exchange, some insurers may offer a reduced premium.
However, this reduction is not fixed or guaranteed. It depends on the insurer and the specific product. A voluntary deductible can lower your premium, but it may also increase what you pay at the time of a claim. So, this decision needs some thought rather than a quick premium comparison alone.
Deductibles in Top-Up and Super Top-Up Plans
This is an important area for Indian buyers, since top-up and super top-up plans are common add-ons to a base health policy.
In many top-up plans, the deductible functions as a threshold. The plan may only start contributing once your total eligible medical expense crosses this threshold amount. A super top-up plan often works similarly, though it may consider the total of multiple claims across the policy year, rather than a single claim.
That said, the exact working can differ meaningfully between insurers and products. Some plans calculate the threshold per claim; others may look at cumulative expenses. Therefore, do not assume that all top-up or super top-up products apply their deductible in the same manner. Always check the policy wording before purchase.
Individual and Family Considerations
Families often assume that every member of a floater policy is treated identically when it comes to deductibles and thresholds. This is not always accurate. Some policy conditions can vary depending on the insured member, the sum insured structure, or the specific product design.
Because of this, families should review the policy at a member level, not just at a household level, before assuming how costs will be shared.
Choosing health insurance for parents may require a closer look at more than the premium. Waiting periods, copay conditions, coverage limits, and hospital access can matter just as much. If you are reviewing cover for older family members, read our guide [Health Insurance for Parents: What Families Should Consider Before Buying] Health Insurance for Parents.
Health Insurance Deductible vs Copay
People frequently confuse a deductible with a copay, but these are different concepts with different effects on your wallet.
A deductible is typically a fixed rupee amount that applies before insurer contribution begins. A copay, on the other hand, is usually a fixed percentage of an eligible claim that you continue to pay, even after the deductible condition is met, depending on the policy.
For example, if your policy has a 10% copay and an eligible claim amount of ₹50,000, you might pay ₹5,000 as your copay share. The remaining ₹45,000 may be settled by the insurer, subject to policy conditions.
| Feature | Deductible | Copay | Coinsurance / Cost Sharing |
|---|---|---|---|
| Basic meaning | A fixed amount paid before insurer contribution starts | A percentage share of the claim paid by the policyholder | A broader term for shared payment between insurer and policyholder |
| How it is calculated | Usually a fixed rupee figure set in the policy | Usually a percentage of the eligible claim amount | Can combine fixed and percentage elements, depending on the product |
| When it may apply | Per claim or per policy year, depending on the plan | Often applies on every eligible claim, depending on the policy | Depends on how the policy defines cost-sharing conditions |
| Example | ₹20,000 deductible on a ₹1,00,000 bill | 10% copay on a ₹50,000 claim | Combination of both deductible and copay in the same policy |
| Effect on personal spending | Reduces insurer’s initial contribution until threshold is crossed | Reduces insurer’s contribution on the entire eligible amount | Can increase overall out-of-pocket cost if both apply together |
| What to check in policy documents | Whether it is compulsory or voluntary, and how it is applied | Whether it applies to all claims or specific categories, such as age-based copay | Whether both a deductible and copay apply on the same claim |
However, this comparison is only a general guide. Exact terms can vary by insurer and policy. Therefore, always check the policy wording before making a decision.
Deductible vs Out-of-Pocket Cost
A deductible is only one part of what you might pay from your own pocket. Other elements, such as copay, sub-limits, room-rent capping, and specific exclusions, can also add to your total personal expense during a claim.
So, when estimating your possible out-of-pocket cost, do not look at the deductible alone. Instead, consider the full combination of policy conditions that might apply to your situation.
How a Health Insurance Deductible Affects Your Costs
There is a common belief that a higher deductible always means a lower premium. This is not entirely accurate, and it can vary by insurer and product.
In some policies, choosing a voluntary deductible may reduce the premium. However, it can also increase the amount you need to pay when an eligible claim occurs. This is a trade-off, not a guaranteed saving.
Because of this, it helps to weigh both sides. A lower premium might feel attractive today, but a higher deductible could mean a larger bill during an actual hospitalisation.
Example: Comparing Two Policy Options
The following is an illustrative example only, using hypothetical figures.
Option A
- No voluntary deductible
- Relatively higher annual premium
- Lower amount payable by the policyholder during a claim
Option B
- Higher voluntary deductible
- Relatively lower annual premium
- Higher amount payable by the policyholder during a claim
If a claim of ₹1,50,000 occurs, Option A might require a smaller personal contribution, while Option B could require a larger one, depending on the deductible amount chosen. Meanwhile, Option B may have saved money on premiums across the year.
This is why premium alone should not decide your choice. The right option depends on your savings, your expected medical needs, and how comfortable you are with a larger one-time payment if a claim arises.
How to Choose the Right Health Insurance Deductible
There is no single answer that suits everyone. A few personal factors can guide the decision.
Consider Your Emergency Savings
Think about how much you could comfortably pay from your own funds if a claim occurred tomorrow. If a higher deductible would strain your savings, a lower-deductible policy may feel more manageable, even at a higher premium.
Health insurance is important, but it may not cover every financial risk a family can face. For example, personal accident insurance and critical illness insurance are designed for different situations and may support a broader protection plan. Therefore, it helps to understand what each type of cover is meant to do. To learn more, read “Personal Accident vs Critical Illness Insurance: What’s the Difference and Do You Need Both?”
Think About Expected Healthcare Needs
Nobody can predict future health conditions. Still, it helps to think honestly about current healthcare use. Someone who visits hospitals or specialists regularly may prefer lower personal cost-sharing, while someone with infrequent medical needs might feel comfortable with a higher deductible.
Consider Family Responsibilities
Parents, spouses, and children often have different healthcare needs. A family with young children or elderly parents may want to review deductible and copay conditions more carefully than an individual buying cover only for themselves.
Health insurance is also only one part of overall financial protection. Personal accident cover and critical illness cover serve different purposes and can complement a health policy in different ways. To understand how these products differ, read our article [Personal Accident vs Critical Illness Insurance: What’s the Difference and Do You Need Both?] [INTERNAL LINK – Personal Accident vs Critical Illness Insurance].
Reviewing overall protection also means looking beyond health cover. For a broader view of financial planning across life stages, you may find it useful to read [Term Insurance at Different Stages of Life: How Much Cover Do You Really Need?] [INTERNAL LINK – Term Insurance at Different Stages of Life].
Compare the Total Policy, Not Just the Premium
A policy is more than its premium and deductible. Before deciding, it helps to compare:
- Sum insured
- Deductible, if applicable
- Copay conditions
- Waiting periods
- Room-rent conditions, where relevant
- Sub-limits, where relevant
- Exclusions
- Cashless hospital network
- Claim process
- Renewal terms
- Overall premium
Not every policy will include all of these features. Even so, reviewing them together gives a more realistic picture than looking at premium or deductible in isolation.
Health insurance is only one part of a family’s financial protection. In addition, life insurance needs can change as income, responsibilities and family commitments grow. Reviewing different types of cover separately can help you understand the role each one plays. For a practical overview, read “Term Insurance at Different Stages of Life: How Much Cover Do You Really Need?”
Questions to Ask Before Choosing a Deductible
A short checklist can make policy comparison easier:
- How much could I comfortably pay from my own savings during a claim?
- Is the deductible compulsory or voluntary in this policy?
- Does it apply per claim, or does another condition decide when it applies?
- How does choosing this deductible affect my premium?
- If this is a top-up or super top-up plan, how does the threshold work?
- Are there other cost-sharing conditions, such as copay or sub-limits?
- What does the policy wording actually say about this deductible?
Keeping these questions handy while speaking with an insurer or agent can make the process far less confusing.
Common Mistakes to Avoid
A few common errors can lead to unpleasant surprises later.
Choosing only by premium. A low premium can look attractive, but it may come with a higher deductible or copay that increases your cost during an actual claim.
Not understanding deductible terms. Some buyers accept a voluntary deductible without fully checking how it applies, then find this out only during a claim.
Confusing deductible with copay. These are different mechanisms, and mixing them up can lead to inaccurate cost expectations.
Ignoring policy wording. Brochures often simplify details. The actual policy document usually has the accurate, binding terms.
Assuming every insurer follows the same structure. Deductible rules can differ significantly across insurers and products, so one policy’s structure should not be assumed for another.
Buying a top-up without understanding its threshold. A top-up plan can be a cost-effective way to increase cover, but only if you understand how its deductible or threshold actually works.
Ignoring exclusions and waiting periods. These conditions can affect whether a claim is even eligible, regardless of the deductible amount.
Not considering family needs. A policy that suits an individual may not automatically suit a family with different age groups and health needs.
How Tesphero Finserv Can Help
Understanding deductibles, copays, and other policy conditions can feel overwhelming, especially with so many products available in the market. Tesphero Finserv can help you understand policy features, compare relevant options, and identify the right questions to ask before buying.
This includes looking closely at aspects such as sum insured, deductible structure, copay conditions, waiting periods, and other coverage details that matter to your specific situation. The goal is to help you approach a health insurance decision with more clarity, rather than relying only on premium comparisons.
For broader consumer information about insurance in India, readers can also refer to resources published by the Insurance Regulatory and Development Authority of India (IRDAI)
Final Thoughts
A health insurance deductible plays a meaningful role in deciding how much you actually pay during a claim, alongside factors like copay, sum insured, and other policy conditions. It is not something to overlook while comparing plans.
The cheapest premium is not automatically the most suitable policy. Instead, take time to understand how much you may need to pay yourself, and what the policy actually covers, before making a final decision.
What is the difference between top-up and super top-up deductibles? A top-up plan’s threshold often applies per claim, while a super top-up plan may consider cumulative claims across the policy year. That said, this can vary by product, so confirm the specific structure before buying.
Should families choose a voluntary deductible? This depends on the family’s savings, health needs, and comfort with personal cost-sharing. There is no single right answer, and each family’s situation is different.
What should I check before choosing a policy with a deductible? Check whether the deductible is compulsory or voluntary, how it is calculated, whether a copay also applies, and how it affects both premium and claim payout. Reading the full policy wording is the most reliable way to confirm these details.
FAQs (Frequently Asked Questions)
About the Author
Tesphero Finserv works with individuals, professionals, and families across India to help them understand insurance and financial products more clearly. The team focuses on breaking down complex policy terms into simple, practical information that readers can use while comparing options.
Tesphero Finserv does not promise guaranteed savings, guaranteed claim outcomes, or a single “best” policy for every reader. Instead, the focus stays on education, so that people can approach financial decisions with more confidence. To learn more about our approach and financial services, visit the About Tesphero Finserv.
Talk to Tesphero Finserv
If you are comparing health insurance policies and are unsure how deductibles, copays, waiting periods, or other conditions may affect you, Tesphero Finserv can help you understand the options more clearly. Reach out to discuss your situation and get help navigating the details before you decide.
- 📧 Email Us: tespherofiserve001@gmail.com
- 🌐 Website & Support Desk: healthfinanceinsights.com
- 📱 Follow Us:
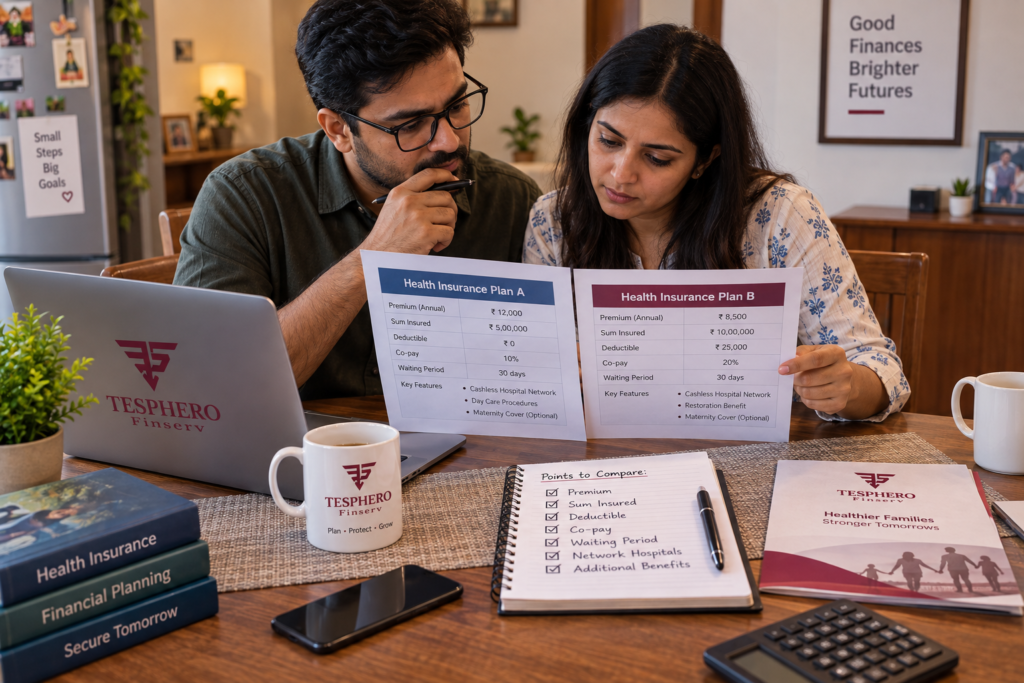
A couple comparing two health insurance plans before making a decision.