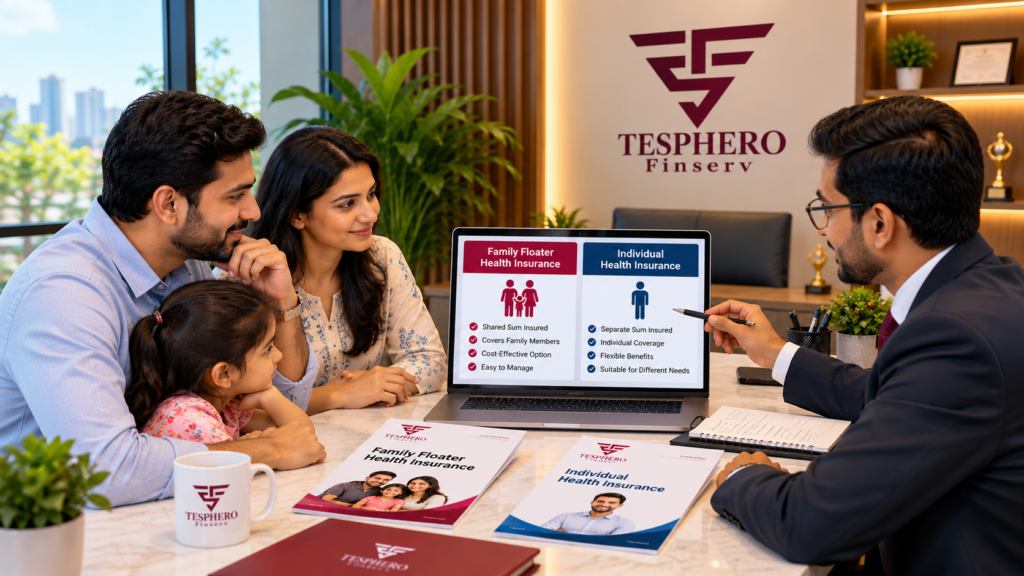
Tesphero Finserv helps families understand the differences between family floater and individual health insurance, including shared coverage, separate benefits, and important policy features, so they can make informed decisions.
Family Floater vs. Individual Health Insurance is a common question for families in India who want suitable medical coverage without spending unnecessarily. Both types of health insurance can help manage eligible hospitalization expenses. However, they differ in how the sum insured is allocated, how claims affect available coverage, and how families can plan for future healthcare needs.
A family floater policy generally provides one shared sum insured for eligible family members. In comparison, individual health insurance provides a separate sum insured for each insured person.
For example, a young couple with one child may prefer a shared policy because it is convenient to manage. On the other hand, a family with elderly parents may benefit from considering separate coverage due to different medical needs.
Still, neither option is automatically better.
The right choice depends on the ages of family members, existing medical conditions, required coverage, policy benefits, and long-term affordability.
In this guide, we will explain both options, compare their benefits and limitations, and discuss how to choose health insurance that fits your family’s circumstances.
Table of Contents
- What Is Family Floater Health Insurance?
- What Is Individual Health Insurance?
- Family Floater vs Individual Health Insurance: Key Differences
- How Does the Sum Insured Work?
- Which Option Is More Affordable?
- How Age and Family Size Affect Your Choice
- When Should You Choose a Family Floater?
- When Is Individual Health Insurance Better?
- Important Policy Features to Compare
- Common Mistakes Families Should Avoid
- How to Choose the Right Health Insurance
- Can You Combine Both Types of Coverage?
- How Tesphero Finserv Can Help
- Frequently Asked Questions
1. What Is Family Floater Health Insurance?
Family floater health insurance covers eligible family members under a common sum insured.
Instead of assigning a separate insured amount to every person, the policy allows covered members to use the available shared coverage for admissible medical expenses.
For example, suppose a family purchases a ₹10 lakh floater policy covering two adults and one dependent child.
If one family member has an admissible hospitalization claim of ₹3 lakh, the remaining base sum insured would generally be ₹7 lakh for the policy year, assuming no restoration or additional benefits apply.
Other covered members can use the remaining amount for eligible claims.
However, if multiple family members require expensive treatment during the same year, the shared coverage may become insufficient.
Key Features of Family Floater Insurance
- A common sum insured for eligible family members
- One policy covering multiple insured people
- Shared coverage available for admissible claims
- Policy benefits and conditions generally apply across covered members
- Restoration or additional benefits may be available, depending on the product
Family floater plans may cover spouses, dependent children, parents, or other eligible relatives. However, the relationships permitted under a policy vary between insurers.
Therefore, always check the policy’s family definition and entry-age conditions.
2. What Is Individual Health Insurance?
Individual health insurance provides a separate sum insured for each insured person.
A family can purchase individual policies for different members based on their ages, healthcare requirements, and financial priorities.
For example, consider a family of three where each person has a separate ₹5 lakh health insurance policy.
If one person makes an admissible claim of ₹3 lakh, the available cover under that person’s policy is generally reduced according to its terms.
However, the other two members retain their own separate coverage.
This arrangement can be useful when family members have different medical needs or when separate protection is preferred.
Key Features of Individual Health Insurance
- A separate sum insured for each insured person
- One person’s claim generally does not reduce another person’s separate cover
- Different coverage amounts can be selected for different members
- Policy features may be chosen according to individual requirements
- Multiple policies may require separate administration and renewals
Although individual coverage offers greater separation of benefits, purchasing several policies can affect the family’s total premium.
Consequently, buyers should compare actual quotations rather than assuming that one structure is always cheaper.
3. Family Floater vs Individual Health Insurance: Key Differences
The main difference between Family Floater vs Individual Health Insurance is how the coverage is shared or allocated.
| Feature | Family Floater Health Insurance | Individual Health Insurance |
|---|---|---|
| Sum insured | Shared among covered family members | Separate for each insured person |
| Claim impact | One person’s claim may reduce the shared balance | One person’s claim generally does not affect another’s separate cover |
| Policy management | Often managed through one policy | May involve multiple policies |
| Premium | Depends on family composition and product pricing | Depends on each person’s cover and pricing |
| Coverage flexibility | Members generally share one policy structure | Different members can choose different policies |
| Multiple hospitalizations | Claims use the shared available amount | Each member uses their separate limit |
| Suitable situations | May suit eligible families comfortable with shared coverage | May suit families with different individual needs |
| Restoration benefits | Available in some products, subject to conditions | Available in some products, subject to conditions |
What Does This Comparison Mean?
A family floater may provide a convenient way to cover several eligible members.
Meanwhile, individual insurance offers separate coverage limits.
However, the right decision should not depend only on this distinction.
Families must also review waiting periods, exclusions, hospital networks, co-payments, deductibles, and restoration provisions.
These features can significantly affect how a policy works when medical treatment is required.
4. How Does the Sum Insured Work?
Understanding the sum insured is one of the most important parts of choosing health insurance.
The sum insured generally represents the maximum amount available for covered claims, subject to policy conditions and applicable benefits.
However, the way this amount is used differs between floater and individual policies.
Example: Family Floater Policy
Suppose three family members share a ₹10 lakh base sum insured.
During the policy year:
- Member A has an admissible claim of ₹4 lakh.
- Member B later has an admissible claim of ₹3 lakh.
- The remaining shared base cover is ₹3 lakh.
This example assumes there are no applicable restoration benefits, additional coverage provisions, or other adjustments.
Therefore, a third major claim could create financial pressure if the remaining coverage is insufficient.
Example: Individual Policies
Now consider three people with separate ₹10 lakh policies.
If Member A makes a ₹4 lakh admissible claim, Member A’s available base cover generally becomes ₹6 lakh.
However, Members B and C continue to have their own ₹10 lakh base coverage, subject to their policy terms.
The difference is clear: a shared cover is used collectively, while individual cover is allocated separately.
Nevertheless, three individual policies of ₹10 lakh each are not equivalent to one ₹10 lakh floater in total available base coverage or necessarily in premium.
As a result, compare realistic coverage amounts and costs before deciding.
5. Family Floater vs Individual Health Insurance: Which Costs Less?
Premium is often the first thing families compare.
A family floater may be competitively priced for certain combinations of younger family members. However, the actual premium depends on the insurer, product, age-related factors, sum insured, underwriting, and selected benefits.
Individual policies may cost more in total in some situations because separate protection is being purchased.
Yet this is not a universal rule.
Factors That Affect Health Insurance Premiums
Age of insured members: Age can influence the premium according to the insurer’s pricing structure.
Medical information: Disclosed health conditions may affect underwriting, subject to applicable regulations and policy rules.
Sum insured: The selected coverage amount can influence pricing.
Policy benefits: Features such as deductibles, co-payments, restoration benefits, and optional add-nos may affect the cost.
Family composition: Adding eligible members can change the floater premium.
Insurer and product: Different products may have different pricing approaches.
Think Beyond the First-Year Premium
A policy should remain financially manageable over time.
For example, the cheapest plan today may not offer suitable protection for future healthcare requirements.
Therefore, families should examine the benefits, limitations, and renewal-related conditions before making a decision.
Also, do not compare only the premium of one floater against the combined premium of several individual policies without checking whether their total coverage and benefits are comparable.
6. How Age and Family Size Affect Your Choice
Age and family composition can influence which coverage structure deserves consideration.
However, there is no single age or family size at which one policy automatically becomes the best option.
Young Couples
A young couple may consider a family floater if both partners are eligible under the same plan.
This arrangement can be convenient because the coverage is shared and the policy may be simpler to manage.
However, couples planning to have children should check maternity benefits, waiting periods, newborn coverage, and the conditions for adding family members.
These benefits are not automatically included in every policy.
Families With Young Children
Parents may prefer to include eligible dependent children under a floater.
However, the family should check the number of children permitted, age limits, and the rules for adding a newborn.
In addition, they should consider whether the shared sum insured is sufficient for multiple medical events during one policy year.
Families With Senior Citizen Parents
Older parents may have different healthcare requirements from younger family members.
For example, they may need coverage that appropriately addresses existing medical conditions, hospital access, co-payments, and other policy conditions.
Consequently, separate policies or a different coverage arrangement may deserve consideration.
For more information, read our previous blog:
Health Insurance for Parents: What Families Should Consider Before Buying
Choosing suitable health insurance for parents
7. When Should You Choose Family Floater Insurance?
A family floater may be worth considering when eligible family members are comfortable sharing one sum insured.
It can be especially practical when the family wants to manage coverage under a common policy.
Situations Where a Floater May Fit
Relatively young family members: A floater may be a practical option when covered members have healthcare needs that make shared protection acceptable.
Convenient policy management: One policy can simplify renewal tracking and document organization.
Shared financial planning: Families can evaluate one common coverage amount against their overall needs.
Suitable benefits: Certain policies may include restoration or other features that support the shared structure.
However, a family floater has limitations.
For example, one large admissible claim can reduce the base cover available to other insured members.
Therefore, the selected sum insured and policy benefits should be assessed carefully.
Also, remember that restoration benefits operate according to specific conditions. They should not be treated as guaranteed unlimited coverage.
8. When Is Individual Health Insurance Better?
Individual health insurance may be useful when different family members need different types or amounts of protection.
For example, one family member may prefer higher coverage, while another may need a policy with different hospital-related benefits.
Separate policies can allow more flexibility.
Situations Where Individual Cover May Fit
Different medical requirements: Each person’s coverage can be assessed independently.
Separate claim limits: One member’s claim generally does not reduce another person’s insured amount.
Different coverage amounts: Family members may select different sums insured according to their circumstances.
Product flexibility: Individuals may compare policies with different features and conditions.
However, separate policies may require additional effort to manage.
For example, renewal dates, documents, insurer communication, and claims procedures may differ.
As a result, the convenience of a floater should be compared with the flexibility of individual coverage.
9. Important Features to Check Before Buying
Choosing between Family Floater vs Individual Health Insurance involves more than comparing premiums and coverage amounts.
Policy conditions can affect both the claim process and out-of-pocket expenses.
9.1 Waiting Periods
Some health insurance policies include waiting periods for specified conditions or benefits.
Coverage for pre-existing diseases may also be subject to applicable waiting-period provisions.
Therefore, check the exact wording and current regulatory requirements.
Do not assume every illness becomes eligible immediately after purchasing a policy.
9.2 Co-Payment
A co-payment requires the insured person to bear a specified portion of an admissible claim, as described in the policy.
For example, a policy may include a percentage-based co-payment provision.
However, the amount payable depends on the relevant terms and claim circumstances.
9.3 Deductibles
A deductible is an amount or threshold that the insured must bear before the relevant policy benefit applies, subject to its conditions.
Deductibles can affect both premiums and out-of-pocket costs.
For a detailed explanation, read:
Health Insurance Deductible: How It Affects Your Costs
Understanding health insurance deductibles
9.4 Room Eligibility and Sub-Limits
Some policies specify room eligibility or limits for particular expenses.
These conditions may affect claim calculations.
Therefore, review them before choosing a policy.
9.5 Restoration Benefits
Some health insurance products provide restoration of the sum insured after specified claim-related conditions are met.
However, restoration rules vary.
For example, a policy may specify when restoration becomes available and whether it can be used for subsequent claims involving the same illness.
Always check these conditions in the policy wording.
9.6 Cashless Hospital Network
A suitable hospital network can be an important consideration.
However, a hospital’s inclusion in a cashless network does not mean every treatment expense will automatically be approved.
Cashless authorization depends on policy terms, admissibility, and the claims process.
For further reading, visit our blog:
Cashless vs Reimbursement Health Insurance Claims: What’s the Difference and Which One Is Better?
Difference between cashless and reimbursement claims
9.7 Exclusions
Exclusions identify circumstances, treatments, or expenses that the policy does not cover.
Therefore, read them carefully.
A policy with a high sum insured may still have limitations that matter to your family’s healthcare needs.
For official insurance information, visit the Insurance Regulatory and Development Authority of India (IRDAI).
10. Common Mistakes Families Should Avoid
Families sometimes make insurance decisions based on assumptions rather than policy details.
Avoiding the following mistakes can make the comparison more useful.
Mistake 1: Choosing Only the Lowest Premium
A lower premium may be attractive.
However, the policy may have different exclusions, deductibles, co-payments, or coverage restrictions.
Therefore, compare benefits alongside cost.
Mistake 2: Assuming Every Family Member Has a Separate Floater Limit
A shared ₹10 lakh floater does not normally provide an independent ₹10 lakh base limit to every covered person.
Instead, covered members use the common amount.
Mistake 3: Ignoring Existing Medical Conditions
Medical information should be disclosed accurately during the application process.
Incomplete or incorrect disclosures may create complications under applicable underwriting and claim rules.
Mistake 4: Overlooking Waiting Periods
Some buyers review waiting periods only when they need treatment.
However, these provisions should be understood before purchase.
Mistake 5: Assuming All Restoration Benefits Are Identical
Restoration features differ between products.
Consequently, the actual conditions matter more than the name of the benefit.
Mistake 6: Not Planning for Family Changes
Marriage, childbirth, ageing parents, and changes in healthcare needs can influence future coverage decisions.
Therefore, check how a policy handles eligible additions and other changes.
Mistake 7: Comparing Unequal Coverage Amounts
A ₹10 lakh family floater and three separate ₹10 lakh individual policies provide different coverage structures.
Their premiums should not be compared without recognizing that difference.
11. How to Choose the Right Health Insurance for Your Family
A practical comparison can help you decide whether shared or separate coverage is more appropriate.
Follow these steps before purchasing a policy.
Step 1: Identify the People Who Need Coverage
Start by listing the family members you want to insure.
Include their ages and relevant healthcare requirements.
Then, check whether they are eligible under the policies being considered.
Step 2: Review Existing Insurance
Some family members may already have individual or employer-provided health insurance.
However, employer coverage may change when employment ends or benefits are revised.
Therefore, consider whether additional independent coverage is needed.
Step 3: Estimate Suitable Coverage
Think about potential medical expenses, financial capacity, existing protection, and family circumstances.
Avoid selecting a sum insured based only on a general recommendation.
Step 4: Compare Floater and Individual Quotations
Request actual quotations from suitable insurers.
Then, compare premiums, coverage limits, waiting periods, exclusions, deductibles, co-payments, and restoration benefits.
Step 5: Consider Multiple Claims
Ask what happens if two family members need hospitalization during the same policy year.
This question is especially important for a shared sum insured.
Step 6: Check Hospital Access
Review the current cashless hospital network and the insurer’s claim procedures.
Also, consider hospitals that are practical for your family’s location and healthcare needs.
Step 7: Read the Policy Documents
Review the policy wording, Customer Information Sheet, and other relevant documents.
If anything is unclear, ask the insurer or authorized advisor for clarification.
Step 8: Consider Long-Term Affordability
Finally, think about whether the arrangement fits your budget beyond the first year.
A suitable policy should balance coverage requirements and financial capacity.
12. Can You Combine Family Floater and Individual Coverage?
Yes, a combination may be suitable for some families.
For example, a couple and their dependent child may have a floater, while their parents maintain separate health insurance policies.
Another family may prefer individual coverage for a member with specific needs.
However, the usefulness of combining policies depends on eligibility, policy terms, premiums, and existing coverage.
Also, holding multiple indemnity health policies does not allow a person to receive reimbursement exceeding the admissible medical expense.
The coordination of claims between policies follows applicable rules and insurer procedures.
Therefore, review how multiple policies work together before making a decision.
13. How Tesphero Finserv Can Help
Choosing health insurance involves understanding both your family’s needs and the details of available policies.
At Tesphero Finserv, we believe insurance decisions should begin with clear information rather than assumptions.
For example, two families with the same number of members may need different coverage arrangements because their ages, medical histories, and financial priorities differ.
A useful policy comparison should consider:
- Family composition and eligibility
- Shared versus separate sum insured
- Coverage amounts and premiums
- Waiting periods and exclusions
- Deductibles and co-payments
- Restoration benefits
- Cashless hospital access
- Long-term affordability
Understanding these factors can help families ask better questions and make more informed choices.
Looking for suitable health insurance options for your family? Connect with Tesphero Finserv to discuss your requirements and compare relevant policy features.
Final premiums, eligibility, benefits, underwriting decisions, and claim outcomes remain subject to insurer terms and applicable regulations.
Conclusion
The decision between Family Floater vs Individual Health Insurance depends on your family’s circumstances.
A family floater may offer convenient shared coverage for eligible members. Meanwhile, individual policies provide separate insured amounts and can offer greater flexibility when healthcare needs differ.
However, neither option is automatically the cheapest or most suitable.
Before buying, compare coverage amounts, waiting periods, co-payments, deductibles, restoration benefits, exclusions, and hospital networks.
Most importantly, choose a policy structure that fits your family’s healthcare requirements and financial capacity.
A careful comparison today can help you better understand the protection available when medical expenses arise.
Frequently Asked Questions
About the Author
Tesphero Finserv – One Stop Financial Hub
Tesphero Finserv shares practical information about insurance, loans, and financial solutions. Our aim is to help individuals, families, and business owners understand important financial products and compare their options with greater clarity.
Disclaimer: This blog is intended for general educational purposes and does not constitute personalized insurance advice. Health insurance benefits, premiums, waiting periods, exclusions, and claims are governed by the applicable policy terms and regulations. Always review current insurer documents before purchasing coverage.
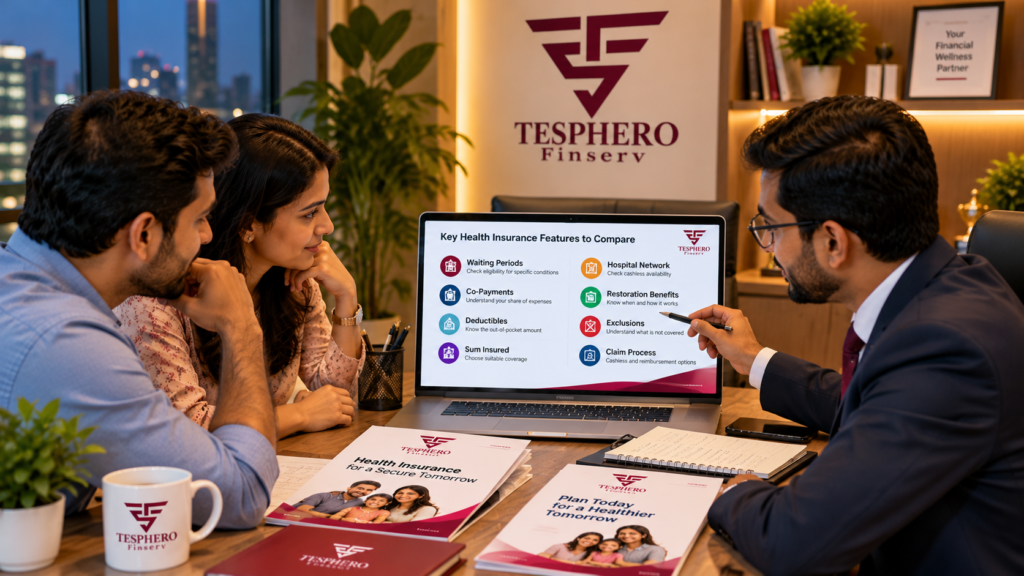
Tesphero Finserv helps families compare important health insurance features, including waiting periods, co-payments, hospital networks, and exclusions, to make informed coverage decisions.