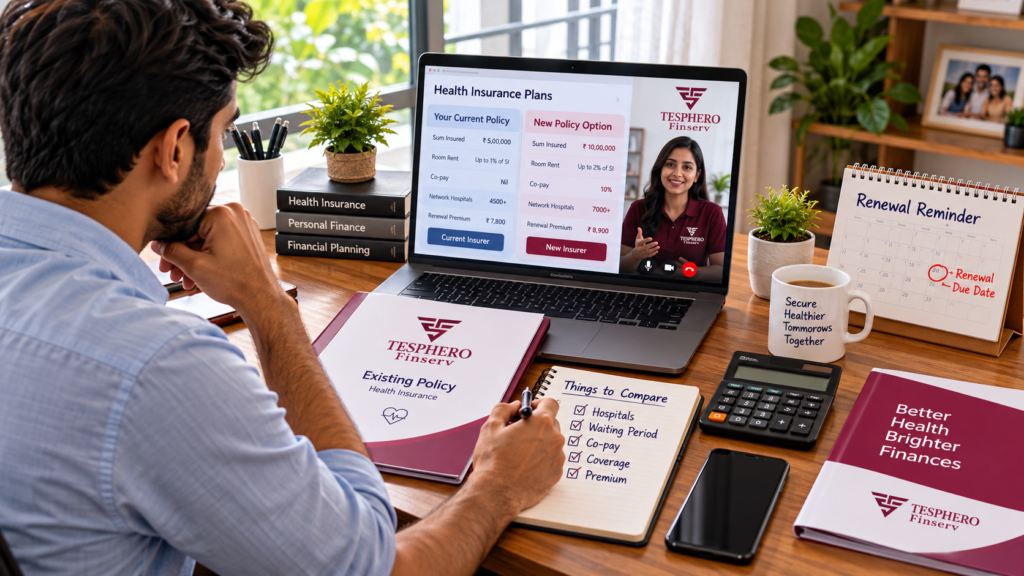
Comparing coverage, waiting periods, co-payments, hospital access and premiums can help you make a more informed health insurance portability decision.
Health Insurance Portability allows policyholders in India to move their health insurance policy from one insurer to another while carrying forward specified continuity credits. This can be useful when your existing policy no longer fits your needs, but switching should involve more than simply comparing premiums.
A lower premium may look attractive. However, hospital network, room-rent conditions, co-payments, exclusions, waiting periods, claim processes, sub-limits, and policy features can have a much bigger impact when you actually need medical care.
The good news is that changing insurers does not necessarily mean losing all the continuity you have built under your existing policy.
IRDAI defines portability as the facility to transfer credits gained for pre-existing diseases and specific waiting periods from one insurer to another. Current IRDAI guidance allows portability for individual, family floater, and group health insurance policies at renewal.
Still, portability is not an automatic upgrade.
Before making the switch, you should understand what transfers, what may change, and whether the new policy genuinely offers a better fit.
Table of Contents
- What Is Health Insurance Portability?
- What Benefits Can You Carry Forward?
- When Should You Consider Porting?
- When Switching May Not Be the Right Move
- What to Compare Before Choosing a New Insurer
- How the Portability Process Works
- Waiting Periods and Portability
- Common Portability Mistakes
- A Practical Portability Checklist
- Final Thoughts
What Is Health Insurance Portability?
Health insurance portability gives an eligible policyholder the option to move from an existing insurer to another insurer at renewal while carrying forward specified continuity credits.
In simple terms, you are not necessarily starting from zero merely because the insurer changes.
Under current IRDAI guidance, portability covers individual, family floater, and group health insurance policies at renewal. The regulator describes portability as transferring credits gained for pre-existing diseases and specific waiting periods from the existing insurer to the acquiring insurer.
Portability and Migration Are Different
These terms can sound similar, but IRDAI distinguishes between them.
Portability generally refers to transferring eligible credits when moving from one insurer to another.
Migration, on the other hand, refers to transferring eligible credits from one health insurance policy to another policy with the same insurer.
Understanding this distinction helps when you speak with an insurer or insurance advisor about changing your cover.
1. What Benefits Can You Carry Forward?
One of the main reasons people hesitate to change health insurers is the fear of losing the benefits they have built over several years.
Portability addresses part of that concern.
For indemnity-based health insurance policies, IRDAI states that eligible portability or migration credits can include credits related to the sum insured, No Claim Bonus, specific waiting periods, waiting period for pre-existing diseases, and the moratorium period.
That makes continuity particularly important.
Pre-Existing Disease Waiting Period Credit
Suppose you have already completed part of the applicable waiting period for pre-existing diseases under your current policy.
Eligible continuity credit can carry forward when you port, subject to the applicable rules and the terms of the new policy.
Therefore, changing insurers does not automatically mean restarting every completed waiting period from day one.
Specific Waiting Period Credit
Health policies may have waiting periods for specified diseases or treatments.
Portability can preserve eligible credit you have already earned toward those periods.
Current IRDAI consumer guidance states that the maximum waiting period under a health insurance policy, including the waiting period for pre-existing diseases, shall not exceed 36 months.
Moratorium Credit
Continuity also matters for the moratorium period.
According to current IRDAI guidance, after 60 continuous months of health insurance coverage, including portability and migration, a policy or claim generally cannot be contested on grounds of non-disclosure or misrepresentation except in cases of established fraud. Different treatment applies to an enhanced sum insured: the 60 months for the enhanced portion runs from the date of enhancement.
This is one reason you should avoid unnecessary breaks in coverage.
2. When Should You Consider Health Insurance Portability?
Changing insurers should solve a real problem or provide a meaningful improvement.
Here are some situations in which reviewing portability may make sense.
Your Current Coverage No Longer Matches Your Needs
Healthcare needs can change over time.
Perhaps you bought a basic policy several years ago. Since then, your family has grown, medical costs have increased, or you now want broader coverage.
In such a case, compare your current policy with available alternatives.
Look beyond the sum insured. Check the actual policy structure as well.
Your Preferred Hospitals Are Not Conveniently Available
Cashless treatment can become easier when your preferred hospitals participate in the insurer’s applicable network or cashless arrangement.
Therefore, check hospital availability in the cities where you and your family are likely to seek treatment.
For families in Indore, for example, reviewing access to relevant local hospitals may matter more than seeing a large nationwide number alone.
Network arrangements can change. Always confirm current information directly with the insurer before making a decision.
Your Policy Has Restrictive Sub-Limits or Conditions
Some policies may include limits or conditions for particular expenses, procedures, room categories, or benefits.
If those conditions no longer suit your requirements, you may want to explore other options.
However, compare the complete wording before switching. A new policy may remove one restriction while introducing another.
Your Premium Has Become Difficult to Manage
Premium is a valid consideration.
Still, price should not become the only reason to port.
A cheaper policy with a higher co-payment, narrower benefits, restrictive room conditions, or unsuitable exclusions may not offer the value you expected.
Instead, compare cost alongside coverage.
3. Poor Service Can Also Trigger a Portability Review
Health insurance is not only a document you purchase once.
Policy servicing matters throughout the relationship.
You may interact with your insurer for endorsements, policy updates, authorization, claims, renewals, or grievances.
If service problems continue, you may consider alternatives.
Before switching, however, separate an isolated problem from a recurring pattern.
One frustrating interaction does not automatically make another insurer a better choice.
Look at the Complete Experience
Consider factors such as:
- clarity of policy communication
- accessibility of support
- digital servicing options
- cashless process
- grievance handling
- policy documentation
- renewal experience
Also remember that claim outcomes depend on policy terms and the facts of each claim.
Do not choose an insurer solely because someone online says that a company “always approves claims.” No insurer can guarantee every claim.
4. When Switching May Not Be the Right Move
Portability gives you a choice, but that does not mean you should use it every year.
Sometimes, keeping the existing policy may remain practical.
For example, your current policy may already provide suitable benefits, acceptable premiums, convenient hospital access, and satisfactory service.
In that situation, changing simply because another advertisement looks attractive may add unnecessary complexity.
Be Careful With Small Premium Differences
Suppose one new policy saves you a modest amount each year.
Before switching, check whether it also changes:
- co-payment requirements
- room eligibility
- sub-limits
- exclusions
- waiting periods
- restoration features
- coverage definitions
- deductibles
- hospital access
A premium saving should be viewed in the context of the entire policy.
Do Not Port Without Reading the New Terms
The new insurer’s product will have its own terms and conditions.
Portability transfers eligible continuity credits; it does not make two policies identical.
Therefore, study the new policy before accepting it.
5. Compare These Factors Before Choosing a New Insurer
A useful portability comparison goes beyond insurer names.
Start with the policy itself.
Sum Insured
Check whether the coverage amount remains suitable for your family and healthcare needs.
If you want to increase the sum insured during the switch, understand how waiting-period and moratorium treatment may apply to the enhanced portion.
Room-Rent Conditions
Review whether the policy places conditions or limits on room eligibility.
These terms can affect how a claim works, depending on the policy wording.
Co-Payment
A co-payment means you bear a specified portion of an admissible claim according to policy terms.
For example, if a policy has an applicable 20% co-payment, the policyholder may need to bear that share of the admissible amount while the insurer handles the remaining eligible portion, subject to policy conditions.
Therefore, do not compare premium without checking co-pay clauses.
Deductibles
A deductible is another important cost-sharing feature.
If you want to understand it in detail, read our guide “Health Insurance Deductibles Explained: How They Affect Your Out-of-Pocket Costs.”
Knowing how deductibles work can help you compare policies more accurately.
Waiting Periods
Check waiting periods for pre-existing diseases and specified treatments.
Also confirm how your accumulated continuity credits will apply after portability.
Exclusions
Every policy has exclusions.
Read them carefully rather than assuming that a broader marketing description means every treatment will receive coverage.
Hospital Access
Review hospitals that matter to your family.
A huge network number has limited practical value if suitable hospitals near your home are difficult to access.
6. Understand the Health Insurance Portability Process
Timing matters when you want to port.
Under current IRDAI guidance, a policyholder who wants portability should generally apply to the new insurer at least 30 days before, but not earlier than 60 days before, the renewal due date. Insurers may consider a portability proposal even when the policyholder approaches within 15 days of renewal, provided the acquiring insurer ensures there is no break in the policy.
Therefore, starting early is the safer practical approach.
Step 1: Review Your Existing Policy
Before looking elsewhere, understand what you already have.
Note your:
- sum insured
- accumulated bonus
- policy start and continuity history
- waiting periods completed
- claims history
- major conditions
- current premium
This creates a useful comparison baseline.
Step 2: Shortlist Suitable New Policies
Compare actual products rather than only insurers.
The same insurer may offer several health plans with different features.
Step 3: Submit the Portability and Proposal Forms
IRDAI says the acquiring insurer provides a portability form authorising it to obtain policy and claim-related information from the existing insurer.
You complete the portability form along with the proposal form and submit them to the new insurer.
Step 4: Insurers Exchange Relevant Information
The acquiring insurer seeks policy and previous claim information from the existing insurer through the Insurance Information Bureau of India portal.
Current IRDAI guidance requires the existing insurer to provide the requested data within 72 hours of receiving the request.
Step 5: The New Insurer Reviews the Proposal
Portability does not mean that you can demand any policy on any terms.
The acquiring insurer evaluates the proposal according to applicable rules and underwriting requirements.
IRDAI’s current consumer information states that the acquiring insurer should decide and communicate its decision immediately, but no later than five days after receiving information from the existing insurer.
7. Portability Does Not Mean Automatic Acceptance
This point deserves attention.
Having the right to request portability does not mean every new insurer must issue every requested plan without assessment.
The new insurer can evaluate the proposal according to its underwriting process and applicable regulations.
Therefore, disclose information accurately.
Do Not Hide Medical Information
Some people worry that mentioning previous illnesses or claims could affect the new proposal.
That is not a reason to hide information.
Complete and accurate disclosure helps the insurer assess the proposal correctly and can reduce disputes later.
Provide the requested medical history, claim information, and other proposal details truthfully.
Portability should never become a reason to provide incomplete information.
8. How Do Waiting Periods Work After Portability?
Waiting periods are often the biggest concern when people consider switching.
IRDAI’s portability framework specifically protects eligible continuity credits rather than treating every port as an entirely new insurance history.
However, the exact impact depends on your existing cover, the new policy, the sum insured, and the applicable terms.
Increasing Cover Needs Extra Attention
Suppose you had an existing policy with a particular sum insured and now want substantially higher coverage.
Do not assume that all continuity benefits automatically apply in exactly the same way to the entire increased amount.
Current IRDAI guidance specifically notes that for the moratorium, when the sum insured increases, the 60 continuous months for the enhanced limits run from the date of enhancement.
Ask the new insurer to explain in writing how waiting periods and continuity credits will apply to your proposed cover.
That clarity can prevent surprises later.
9. Think About Your Broader Protection Needs
Portability can improve the fit of your health policy, but health insurance addresses only one part of financial protection.
For example, a health policy generally deals with eligible medical expenses according to its terms.
Critical illness insurance works differently and may provide a defined benefit when a covered condition meets the policy requirements.
Our guide “Critical Illness Insurance vs Health Insurance: Understanding the Difference” explains these differences in greater detail.
Likewise, families should not treat health insurance as a replacement for life cover.
If you are reviewing your protection because of marriage, children, a home loan, or other responsibilities, you may also find “Term Insurance at Different Stages of Life: How Much Cover Do You Really Need?” useful.
Each product addresses a different financial risk.
10. Common Health Insurance Portability Mistakes
A rushed switch can create problems that careful comparison might prevent.
One common mistake is choosing solely on premium. Another is assuming that every feature of the old policy will continue unchanged.
People may also overlook co-payments, exclusions, room conditions, hospital access, or new-policy definitions.
Waiting until the last moment creates another avoidable risk.
Since portability normally takes place around renewal, start the review well before the due date.
Finally, avoid allowing the policy to lapse while you are deciding.
Continuity matters for several health insurance benefits.
Quick Comparison: Stay or Review Portability?
| Situation | What to Review |
|---|---|
| Current cover suits your needs | Compare before making an unnecessary change |
| Premium has risen | Check benefits and cost-sharing, not price alone |
| Preferred hospitals are inconvenient | Review current hospital access with alternatives |
| Policy has restrictive conditions | Compare equivalent clauses in new policies |
| Service problems keep recurring | Assess other insurers and servicing options |
| Family needs have changed | Review cover amount and policy structure |
| You want higher coverage | Check treatment of enhanced sum insured |
| Renewal is approaching | Begin the portability review early |
This table should guide your review rather than decide for you.
Individual requirements can differ considerably.
11. A Practical Health Insurance Portability Checklist
Before submitting a portability request, compare both policies side by side.
Check the sum insured and accumulated benefits first.
Next, review room eligibility, co-payment, deductibles, waiting periods, exclusions, sub-limits, restoration benefits, and hospital access.
After that, examine the insurer’s servicing process and policy wording.
Also confirm:
- which continuity credits will transfer
- treatment of any increased sum insured
- premium for all insured members
- applicable medical underwriting
- policy-specific waiting periods
- relevant exclusions
- renewal terms
- required documents
- portability timeline
Keep copies of forms and important communication.
Most importantly, ask questions before accepting the new policy rather than after a claim arises.
12. How Tesphero Finserv Can Help
Comparing health insurance policies can become confusing because premiums are only one part of the decision.
Tesphero Finserv can help customers review policy features, understand portability considerations, and compare health insurance options according to their requirements.
The process should begin with your existing cover.
From there, you can identify what you want to improve—whether that involves coverage structure, hospital access, cost-sharing conditions, policy features, or another practical concern.
The goal is not to switch insurers simply because portability exists.
Instead, the decision should come from a careful comparison of the existing policy and the proposed alternative.
Policy issuance, underwriting, terms, and claims remain subject to the respective insurer’s rules and applicable policy conditions.
Final Thoughts
Health Insurance Portability gives policyholders in India a useful way to consider another insurer without necessarily losing eligible continuity credits built under their existing health cover.
However, switching should have a clear purpose.
Do not focus only on a cheaper premium or an attractive advertisement. Instead, compare coverage, waiting periods, hospital access, co-payments, deductibles, exclusions, sub-limits, policy wording, and servicing.
Timing matters as well.
Current IRDAI guidance says policyholders should generally apply between 60 and 30 days before the renewal due date, although insurers may consider certain later requests subject to the applicable conditions.
A carefully evaluated port can help you move toward a policy that better matches your current needs. A rushed switch, however, may simply replace one set of conditions with another.
Frequently Asked Questions
About the Author
Tesphero Finserv helps individuals and families understand insurance and financial protection options practically. The focus is on helping customers compare relevant features, understand policy conditions, and make informed decisions based on their requirements.
Insurance coverage, underwriting, premiums, exclusions, waiting periods, policy issuance, and claims remain subject to the applicable insurer’s policy terms and conditions.
Considering a Health Insurance Switch?
If your current health insurance policy no longer matches your requirements, Tesphero Finserv can help you understand the factors involved in portability and compare suitable options before renewal.
Review the details early so you have enough time to understand the proposed policy before making a decision.