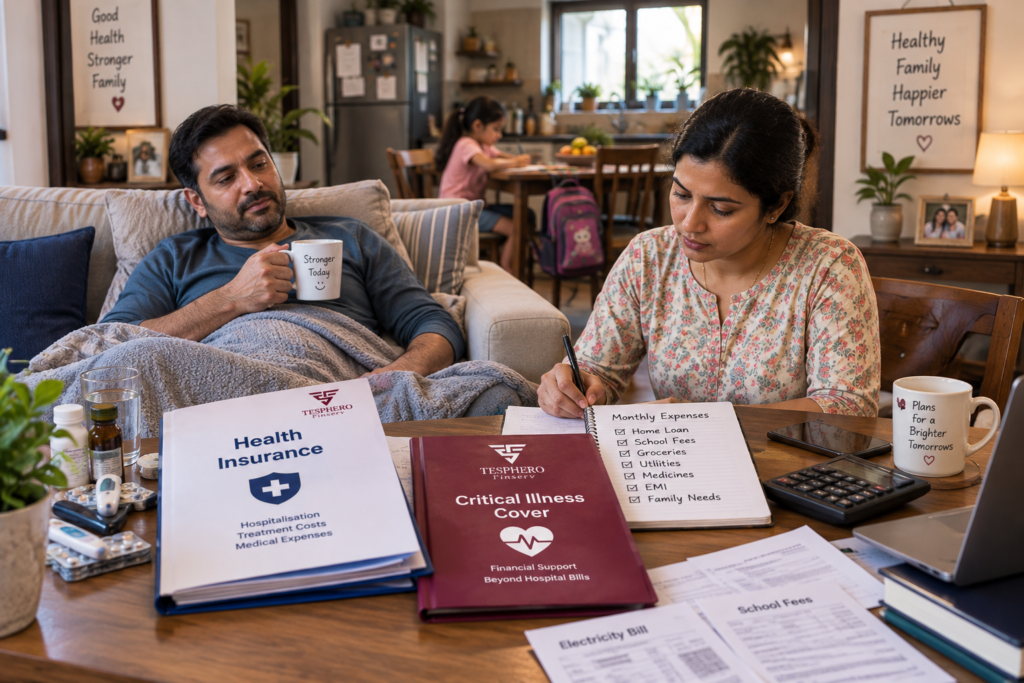
A critical illness can affect more than hospital expenses, making wider financial planning important for families.
Critical Illness Insurance vs. Health Insurance can be confusing because both are connected to medical and financial protection. However, they are designed to handle different types of financial needs.
Imagine a person is diagnosed with a serious illness. Hospital treatment may lead to medical bills. At the same time, the person may need to take a long break from work. Travel, home care, rehabilitation, and regular household expenses may continue as well.
A health insurance policy may help with eligible medical expenses, depending on its terms. Critical illness insurance, on the other hand, is commonly structured to pay a fixed benefit when a covered critical illness meets the policy definition and claim conditions. IRDAI describes indemnity-based health insurance as paying actual medical expenses up to the sum insured, while benefit-based insurance pays a fixed lump sum regardless of actual medical expenses, subject to policy terms.
Therefore, these two forms of cover should not automatically be treated as substitutes.
Understanding the difference can help families review their protection more clearly. This guide explains how both types of insurance generally work, where they differ, and what you should check before buying.
Table of Contents
- Understanding Health Insurance
- How Critical Illness Insurance Works
- The Main Difference Between the Two
- What Each Type of Policy May Cover
- How Claims and Payouts Can Differ
- When Critical Illness Cover May Be Useful
- Important Policy Conditions to Check
- Common Insurance Mistakes to Avoid
- Building Broader Financial Protection
- How Tesphero Finserv Can Help
Understanding Health Insurance
Health insurance is designed to provide financial protection against covered medical expenses.
IRDAI defines health insurance broadly as insurance providing benefits related to sickness and medical, surgical, or hospital expenses, among other covered areas. Its consumer guidance also notes that health policies can take different forms.
For many people, the most familiar form is an indemnity-based health insurance policy.
Under this structure, the insurer pays eligible medical expenses up to the applicable policy limits and according to the policy terms.
A Simple Health Insurance Example
Suppose a person has an indemnity-based health policy.
Later, that person needs hospital treatment for a covered medical condition.
The eligible hospital expenses may be considered under the policy. However, the amount actually payable can depend on several factors.
These may include:
- sum insured
- policy exclusions
- waiting periods
- deductibles
- co-payment conditions
- sub-limits
- room-rent conditions
- eligible medical expenses
- other policy terms
Therefore, having a ₹10 lakh sum insured does not automatically mean every medical expense up to ₹10 lakh will be paid.
The policy wording still matters.
Cashless and Reimbursement Claims
Depending on the policy and circumstances, health insurance claims may involve a cashless facility or reimbursement.
With an eligible cashless claim, the insurer or its claims arrangement may settle approved expenses with an eligible hospital according to policy terms.
In a reimbursement situation, the policyholder generally pays the medical expenses first and later submits the required documents for consideration.
IRDAI advises buyers to review eligible hospitals and healthcare providers for treatment and cashless payments when choosing a health policy.
How Critical Illness Insurance Works
Critical illness insurance usually works differently from a standard indemnity-based hospitalization policy.
A critical illness benefit policy generally provides a fixed lump-sum amount when the insured person is diagnosed with a specified critical illness or undergoes a specified covered procedure, provided the policy conditions are satisfied. IRDAI’s policyholder guidance describes this fixed benefit as a way to help manage direct and indirect financial consequences of a critical illness.
That difference is important.
The payout is not necessarily based on the exact hospital bill.
Only Specified Conditions Are Covered
The term “critical illness” does not mean every serious medical condition will automatically qualify.
A policy contains a defined list of covered illnesses or procedures. It also sets out the definitions and conditions that must be satisfied for a claim.
For example, a policy may include certain specified forms or severity levels of serious conditions. However, the exact list and definitions can vary between products.
IRDAI has also issued standardization guidance and modifications concerning definitions of critical illnesses, reinforcing why buyers should read the actual product wording rather than relying only on the name of an illness.
Therefore, never assume that a diagnosis qualifies automatically.
Check the policy definition.
The Payout May Be Used Beyond Hospital Bills
A fixed-benefit payout can be useful because a serious illness may create expenses beyond hospital treatment.
Depending on the family’s circumstances, money may be needed for:
- household expenses
- travel for treatment
- rehabilitation
- recovery-related costs
- support at home
- existing financial commitments
- temporary reduction in income
How the payout can be used depends on the policy and claim structure, so buyers should review the applicable terms carefully.
Critical Illness Insurance vs Health Insurance: The Main Difference
The easiest way to understand the difference is to look at what triggers the benefit and how the claim is structured.
A typical indemnity health policy focuses on eligible medical expenses.
A typical critical illness benefit policy focuses on the occurrence of a specifically covered condition that meets the policy definition.
Here is a simple comparison:
| Factor | Health Insurance | Critical Illness Insurance |
|---|---|---|
| Main purpose | Helps with eligible medical expenses | Provides financial support after a covered critical illness |
| Common claim structure | Indemnity-based | Benefit-based |
| Payout basis | Eligible actual expenses, subject to policy terms | Fixed benefit, subject to policy conditions |
| Hospital bill required? | Usually relevant for an indemnity claim | Payout is generally not based on the exact bill |
| Conditions covered | Depends on the health policy | Only specified critical illnesses/procedures |
| Non-medical financial impact | Generally not the main purpose of indemnity cover | Lump sum may help manage broader financial impact |
| Claim amount | Depends on eligible expenses and policy limits | Defined benefit amount, if claim conditions are met |
| Policy conditions | Waiting periods, exclusions, co-pay, limits, etc. may apply | Definitions, waiting/survival conditions or other terms may apply depending on product |
This comparison is general.
Actual products can be structured differently. Therefore, always check the policy wording, Customer Information Sheet, benefit structure, exclusions, and claim conditions before making a decision.
What Health Insurance May Help Cover
Health insurance can provide broader medical-expense protection, depending on the product.
A policy may include eligible hospitalization-related expenses and other specified benefits.
However, the exact scope varies.
Hospitalization Expenses
Many health policies are designed around hospitalization.
Eligible expenses may include certain hospital charges, treatment costs, medical procedures, and other covered expenses.
Still, limits or conditions may apply.
IRDAI specifically advises consumers to pay attention to restrictions such as room-rent and ICU limits, waiting periods, exclusions, sub-limits, and co-payment requirements.
Pre- and Post-Hospitalization
Some policies may cover specified medical expenses before and after hospitalization for defined periods.
The duration and eligible expenses depend on the policy.
Therefore, avoid assuming that every expense before or after treatment will be covered.
Day-Care and Other Benefits
Medical treatment has changed over time. Some procedures may not require a traditional overnight hospital stay.
Health products can include day-care and other forms of treatment depending on their design and terms.
Again, the actual policy should be checked.
What Critical Illness Insurance May Provide
Critical illness insurance generally focuses on a defined event rather than a complete range of hospital expenses.
The benefit may become payable when a covered condition meets the required definition and other claim conditions.
Fixed Financial Support
Suppose a person has ₹10 lakh of qualifying critical illness benefit cover.
If that person experiences a covered illness and satisfies all relevant claim conditions, the applicable benefit may be paid according to the policy.
The hospital bill does not necessarily need to equal ₹10 lakh for a benefit-based claim.
This is different from an indemnity structure, where eligible actual expenses form the basis of the claim. IRDAI makes this distinction between indemnity and benefit-based health policies.
Why a Lump Sum Can Matter
A major illness can affect more than medical bills.
Imagine the insured person is the primary earner in the family and cannot work for several months.
Health insurance may address eligible treatment expenses according to policy terms. However, rent or home-loan payments, school fees, groceries, and other household commitments can continue.
A fixed critical illness benefit may provide an additional financial resource in such a situation, subject to the policy conditions.
How Claims Can Work Differently
This is one of the most important areas to understand.
Health Insurance Claim
Consider an illustrative example.
A policyholder has an indemnity health insurance policy with a ₹10 lakh sum insured.
The person later incurs ₹3 lakh in hospital expenses.
This does not automatically mean the insurer will pay exactly ₹3 lakh.
The final eligible amount can depend on:
- covered expenses
- exclusions
- deductibles
- co-payment
- sub-limits
- waiting periods
- policy conditions
So, the claim is assessed according to the policy.
If deductibles are confusing, read our guide “Health Insurance Deductibles Explained: How They Affect Your Out-of-Pocket Costs.”
Critical Illness Claim
Now consider a person with a separate benefit-based critical illness policy.
Suppose the policy provides a fixed ₹10 lakh benefit for covered conditions.
If a diagnosed condition meets the policy’s definition and all claim requirements, the applicable fixed benefit may become payable according to the contract.
The amount is generally not calculated from the exact hospital bill in the same way as an indemnity claim.
This example is only for explanation. It is not a promise of claim payment.
Can Health Insurance Cover a Critical Illness Too?
This is where many people become confused.
A regular health insurance policy may cover eligible hospitalization expenses arising from a serious illness, provided the treatment and condition fall within the policy terms.
However, that does not make it identical to critical illness benefit insurance.
The difference is the purpose and payout structure.
For example, health insurance may help pay eligible hospital treatment costs.
Critical illness benefit insurance may provide a predetermined lump sum after a qualifying diagnosis or covered procedure.
Therefore, the question is not simply:
“Does my health policy cover cancer or heart treatment?”
A better set of questions would be:
What expenses does my health policy cover?
Does my policy have relevant limits or waiting periods?
Do I have any separate critical illness benefit?
What conditions and definitions apply to that benefit?
These questions create a clearer picture.
When Critical Illness Cover May Be Worth Considering
There is no single insurance combination that suits every person.
Financial responsibilities, savings, existing insurance, age, income, and family circumstances can all matter.
However, some situations may make people want to explore critical illness protection in addition to their existing medical cover.
When the Family Depends Heavily on One Income
A serious illness may affect a person’s ability to work.
If most household expenses depend on one income, a long recovery period could create financial pressure.
Therefore, income disruption may be worth considering when reviewing protection.
When Financial Commitments Are High
Home loans, education costs, household expenses, and other commitments may continue during treatment and recovery.
A person with significant ongoing commitments may want to consider how those expenses would be managed if income were temporarily reduced.
When Existing Savings Are Limited
Emergency savings can help families manage unexpected expenses.
However, not everyone has enough savings to support a long recovery period.
Insurance cannot replace good financial planning, but understanding the possible financial impact of serious illness can help when reviewing cover.
When You Want Protection Beyond Hospital Bills
A health policy and a critical illness benefit can address different financial needs.
For this reason, comparing them only on premium may not provide the full picture.
Important Conditions to Check Before Buying
Do not choose a policy only from the headline benefit amount.
Read the details.
Covered Critical Illnesses
Check the exact list of covered conditions.
Then read how each relevant illness is defined.
A familiar disease name on a brochure does not necessarily mean every stage or form of that disease qualifies.
Waiting Periods
A policy may have waiting periods before certain coverage becomes effective.
The exact rules depend on the product.
Therefore, check the applicable waiting periods before buying.
Survival Conditions
Some critical illness products may include survival-related conditions after diagnosis or the covered event.
Do not assume every policy follows the same rule.
Read the specific wording carefully.
Exclusions
Every policy has terms that define what is and is not covered.
Review exclusions before making a purchase.
This is particularly important because discovering an exclusion only at claim time can create unpleasant surprises.
Policy Continuation After a Claim
Some benefit policies may terminate after the insured benefit is paid, depending on product design.
IRDAI’s consumer guidance notes that a critical illness benefit policy will usually cease after the lump-sum benefit is paid.
However, the actual contract should always be checked.
Common Mistakes People Make
Assuming Both Policies Do the Same Job
They can overlap around serious health events, but their financial structure can be different.
Health insurance commonly focuses on eligible medical expenses. Critical illness benefit cover generally focuses on a fixed payment after a qualifying covered event.
Looking Only at the Number of Illnesses Covered
A policy advertising a large number of covered illnesses may look attractive.
However, the number alone does not tell you whether the cover fits your needs.
Definitions, exclusions, waiting periods, benefit amount, and claim conditions also matter.
Choosing Only by Premium
A lower premium may look attractive, but price is only one factor.
Compare what the policy actually covers.
Also review conditions that may affect a future claim.
Hiding Medical Information
Accurate disclosure is important when applying for insurance.
IRDAI specifically advises buyers to disclose per-existing health problems because concealing relevant facts can lead to disputes and may affect claims or the policy.
Answer proposal-form questions carefully and truthfully.
Assuming Employer Insurance Is Always Enough
Employer-provided health cover can be useful.
However, the amount and benefits depend on the employer’s group policy.
Employment can also change.
Therefore, families may want to understand exactly what workplace insurance provides instead of assuming it covers every long-term requirement.
Critical Illness Cover Is Only One Part of Financial Protection
Health risks are not the only risks a family may need to consider.
For example, an accident can create a different financial situation from a serious illness.
Personal accident insurance and critical illness insurance are designed around different insured events and policy conditions.
If you want to understand that distinction, read “Personal Accident vs Critical Illness Insurance: What’s the Difference and Do You Need Both?”
Life protection is another separate consideration.
A family’s need for term insurance can change as income, loans, dependents, and responsibilities change over time. Therefore, it helps to review each type of insurance according to the financial risk it is designed to address.
For a broader overview, read “Term Insurance at Different Stages of Life: How Much Cover Do You Really Need?”
Critical Illness Insurance vs Health Insurance: Questions to Ask
Before selecting or changing cover, ask practical questions.
- What type of health insurance do I already have?
- What is my current sum insured?
- Which medical expenses are covered?
- Are there deductibles or co-payments?
- Which waiting periods apply?
- Does my existing policy include any critical illness benefit?
- Which illnesses are listed under the critical illness cover?
- How does the policy define those conditions?
- Is the critical illness benefit fixed?
- Are there survival-related conditions?
- What exclusions apply?
- What happens to the policy after a critical illness claim?
- How would my family manage if my income stopped temporarily?
- How much emergency savings do we have?
- Are my dependents covered appropriately?
The answers can help you understand gaps in your current protection.
However, avoid comparing policies from marketing brochures alone.
The policy wording and Customer Information Sheet are more important.
How Tesphero Finserv Can Help
Insurance can become confusing when several policies appear to offer similar protection.
Tesphero Finserv helps individuals and families understand insurance options based on their requirements, financial responsibilities, and existing cover.
The aim is to make important policy features easier to compare. This may include looking at health insurance, critical illness protection, term insurance, personal accident cover, and other relevant financial protection options.
However, insurance should not be selected only from a premium quote or headline sum insured.
Coverage conditions, exclusions, waiting periods, co-payment, deductibles, and other terms may affect how a policy works.
For official insurance information, consumer guidance, registered insurers, and regulatory updates in India, you can also refer to the Insurance Regulatory and Development Authority of India (IRDAI). IRDAI advises consumers to understand policy terms, restrictions, waiting periods, exclusions, sub-limits, co-payments, and eligible hospitals before buying health insurance.
Final Thoughts
Understanding Critical Illness Insurance vs Health Insurance becomes easier when you focus on the purpose of each type of cover.
An indemnity-based health policy generally helps with eligible medical expenses according to policy terms.
A benefit-based critical illness policy generally pays a fixed amount when a covered illness or procedure satisfies the policy’s definition and claim conditions.
One focuses mainly on eligible healthcare expenses. The other can provide a fixed financial benefit following a qualifying critical illness event.
That does not mean everyone needs the same combination.
Your existing cover, income, dependents, savings, financial commitments, and policy terms all matter.
Therefore, start by understanding what you already have.
Then review possible financial gaps.
Most importantly, read the actual policy documents before making a decision. Insurance works best when you understand not only the benefit amount, but also the conditions attached to it.
Frequently Asked Questions
About the Author
Tesphero Finserv helps individuals and families understand financial protection options more simply and practically. Its focus includes health insurance, term insurance, personal accident protection, critical illness cover, and related financial solutions. Rather than looking only at premiums, Tesphero Finserv encourages customers to understand policy features, coverage conditions, exclusions, waiting periods, and their own financial responsibilities. Since insurance needs can vary from one family to another, the aim is to support informed comparisons based on individual requirements and available policy options.
Want to Review Your Insurance Protection?
If you already have health insurance but are unsure how your family would manage the wider financial impact of a serious illness, it may be useful to review your existing protection.
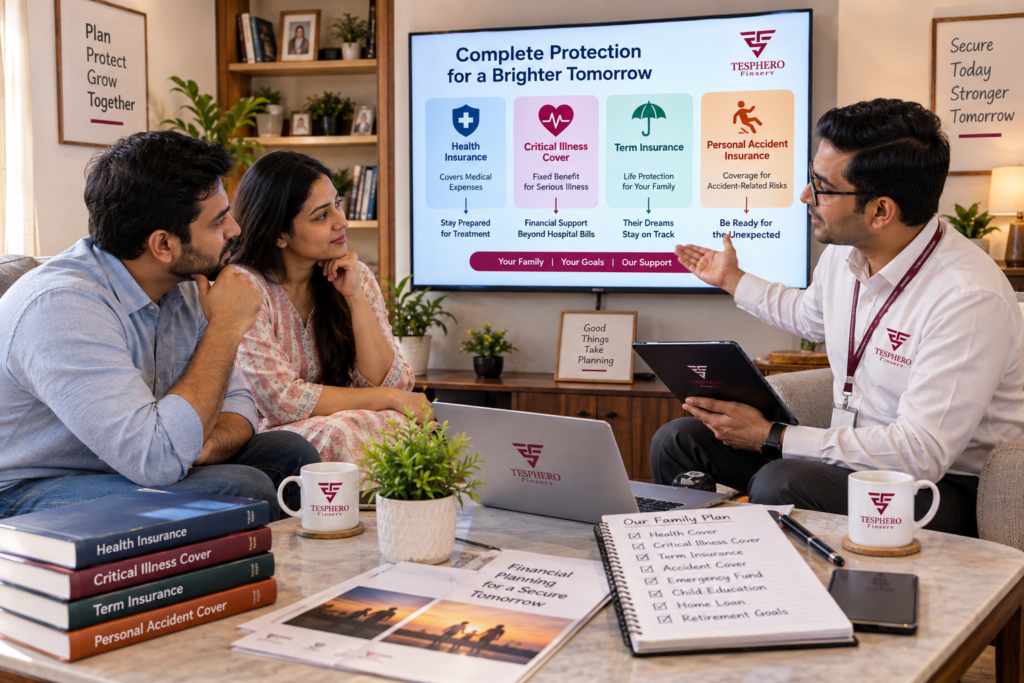
Reviewing different types of insurance separately can help families understand the role each cover may play.