tesphero.com

Finserv

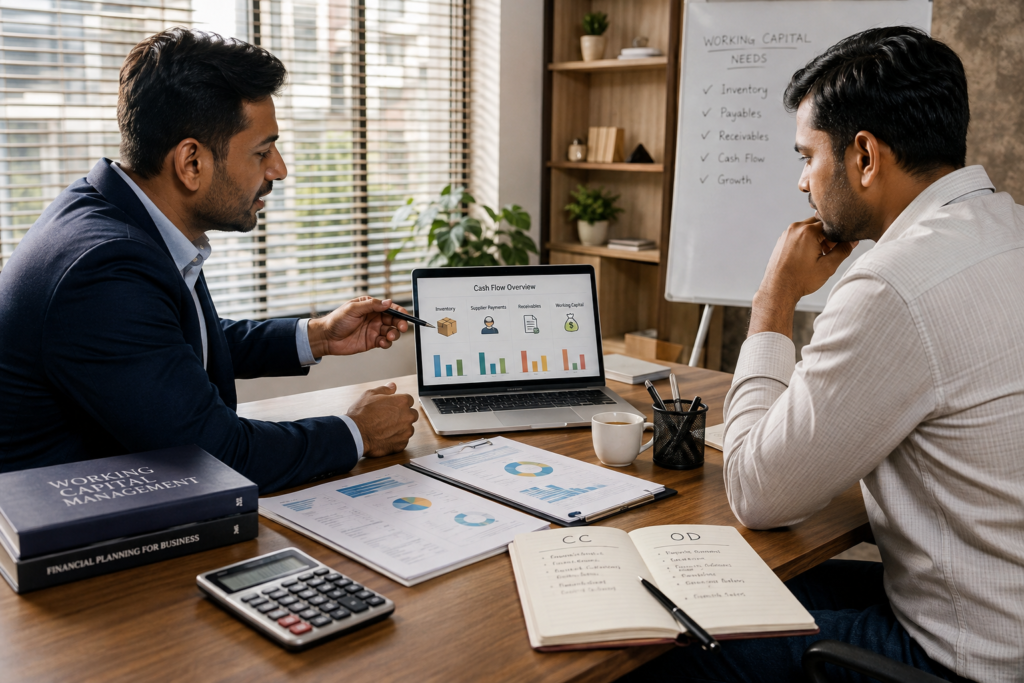
Financial advisor explaining working capital options to an MSME business owner
Finserv

CC vs OD for Business: Which Working Capital Facility Is Right for Your MSME?

Running a business requires more than a good product or service. Even when sales are growing, businesses often face a common challenge: managing day-to-day cash flow. A customer may place an order today but pay after 30 or 60 days. Meanwhile, the business still needs to pay suppliers, salaries, rent, electricity bills, transportation costs, and other operating expenses. This is where working capital becomes important. For many Micro, Small and Medium Enterprises (MSMEs), access to short-term funds can help manage temporary cash-flow gaps and keep regular operations running smoothly. Two commonly used working capital facilities are Cash Credit (CC) and Overdraft (OD). At first glance, they may appear similar because both can provide access to funds when a business needs additional liquidity. However, their structure, usage, security requirements, and suitability can differ depending on the business and the type of financial arrangement. So, the question is: CC vs OD—Which working capital facility is right for your MSME? The answer depends on your business model, cash flow cycle, funding requirements, security available, and how frequently you need access to short-term funds. In this guide, we’ll understand the difference between Cash Credit and Overdraft, how each facility generally works, and what MSMEs should consider before choosing one. Every financial decision—whether it’s choosing the right working capital facility for your business or understanding how insurance claims work—requires careful planning. If you’re also looking to understand the health insurance claim process, read our guide on Cashless vs Reimbursement Health Insurance Claims: What’s the Difference and Which One Is Better? 1. What Is Working Capital? Before comparing CC and OD, it is important to understand the purpose of working capital. Working capital is essentially the money a business uses to manage its day-to-day operational requirements. For example, a business may need funds for: The timing of business income and expenses is not always the same. For instance, imagine a manufacturing business receives a large order from a customer. The business needs to purchase raw materials and start production immediately. However, the customer may make the payment only after the finished goods are delivered. The business is profitable on paper, but it may still experience a temporary cash flow gap. Working capital facilities can help businesses manage such situations. MSMEs play a vital role in India’s economy, contributing significantly to employment and economic growth. Businesses looking for official information, schemes, and resources can visit the Ministry of Micro, Small and Medium Enterprises (MSME), Government of India. 2. What Is Cash Credit (CC)? Cash Credit, commonly known as CC, is a working capital facility generally designed to help businesses manage ongoing operational expenses and short-term funding requirements. Under a CC facility, a business is typically provided with a sanctioned limit based on factors such as its financial position, business activity, estimated working capital requirements, and other applicable lending criteria. The business can generally draw funds within the approved limit, subject to the terms and conditions of the facility. One of the key features of CC is that it is commonly associated with stock and receivables as security. For example, a business may have inventory worth a certain amount and outstanding payments expected from customers. Depending on the lender’s assessment and applicable terms, these assets may form part of the basis for determining the available working capital facility. The business can then use the facility to manage its operational cash flow. Example Suppose an MSME has a sanctioned CC limit of ₹20 lakh. The business may not need the entire ₹20 lakh every day. If it uses ₹8 lakh for purchasing inventory, the interest calculation is generally linked to the amount utilised, subject to the facility’s specific terms. As the business receives customer payments and repays part of the utilised amount, the available drawing capacity may change according to the applicable arrangement. This flexibility can be useful for businesses with regular inventory and receivables cycles. 3. What Is an Overdraft (OD)? An Overdraft, commonly known as OD, allows a customer or business to withdraw or use funds beyond the available balance in an account, up to an approved limit. The exact structure of an OD facility can vary depending on the lender and the type of facility. Unlike a traditional term loan, an OD facility is generally designed to provide flexibility in accessing short-term funds. A business may use the available limit when it faces a temporary cash flow requirement and repay the amount when funds come in. For example, suppose a business has an OD limit of ₹10 lakh. It may use ₹3 lakh to manage a temporary payment requirement and later repay the amount when it receives customer payments. The available limit can then become accessible again, subject to the terms of the facility. Depending on the type of OD, the facility may be secured against an asset or may be structured differently based on the borrower’s profile and lender requirements. 4. CC vs OD: What’s the Difference? Although both CC and OD can provide businesses with access to short-term funds, they are not necessarily the same. The biggest differences usually relate to purpose, structure, security, and how the facility is operated. Let’s look at the key differences. Purpose A CC facility is generally structured around a business’s regular working capital requirements, such as inventory and receivables. An OD facility may be more suitable for managing specific short-term liquidity gaps, depending on the facility structure and lender terms. Security CC facilities are commonly associated with working capital assets such as stock and receivables. OD facilities may be secured against assets such as property or other acceptable security, depending on the arrangement. However, the exact security requirements can vary from one lender and facility to another. Usage CC is often used by businesses with a regular operating cycle involving inventory, sales, and customer receivables. OD may be useful when a business needs flexible access to funds for short-term cash flow requirements. Limit The approved limit for either facility depends on factors such as the business’s financial
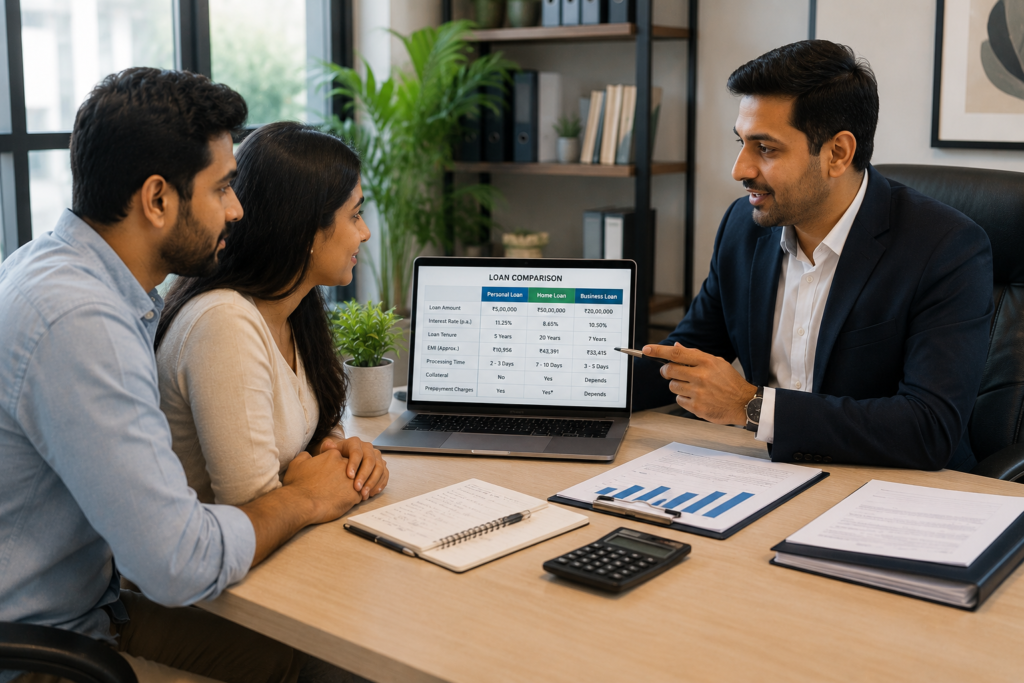
The right loan begins with understanding your financial requirement and choosing an option that matches your actual needs.
Finserv, Tesphero-blogs

How to Choose the Right Loan for Your Financial Needs: A Practical Guide for Borrowers

/choose-right-loan-for-financial-needs Taking a loan is an important financial decision. Whether you need funds for a personal requirement, a new business, a home, or an important investment, the right loan can help you manage your financial goals more effectively. But choosing a loan should not be based only on the amount you can borrow or the interest rate advertised by a lender. The right loan depends on several factors, including your purpose, repayment capacity, income, existing financial commitments, loan tenure, and overall financial situation. A loan that works well for one borrower may not necessarily be the right choice for someone else.If you’re also planning your overall financial protection, you may find our guide on 10 Things You Must Check Before Buying a Health Insurance Policy in India helpful. This is why understanding your options before making a decision is important. In this guide, we’ll discuss how borrowers can evaluate different loan options, understand their financial requirements, and make a more informed borrowing decision. Why Choosing the Right Loan Matters A loan is not just about receiving money today. It also creates a financial commitment that may continue for months or years. Before choosing a loan, you should consider: Answering these questions can help you avoid borrowing more than necessary or selecting a loan that becomes difficult to manage later. The goal should not simply be to find a loan that gives you the highest amount. The goal should be to find a loan that fits your financial needs and repayment capacity. 1. Start by Understanding Why You Need the Loan The first step in choosing a loan is understanding its purpose. Different financial requirements may require different types of loans. For example: Personal Financial Needs If you need funds for a personal requirement, education, medical expenses, travel, or another planned expense, a personal loan may be one possible option depending on your eligibility and financial situation. Home Purchase If you’re planning to purchase a residential property, a home loan is generally structured specifically for property financing and typically comes with a longer repayment period. Business Requirements Businesses may require funds for working capital, expansion, equipment, inventory, or other operational needs. Depending on the requirement, a business loan or project finance solution may be considered. Property-Related Requirements If you are involved in real estate transactions or require financing against eligible property, specific loan options may be available based on the lender’s policies and your eligibility. Understanding the purpose of borrowing helps narrow down the options and makes the decision-making process more focused. 2. Decide How Much You Actually Need to Borrow One common mistake borrowers make is applying for the maximum loan amount available to them instead of calculating how much they actually need. A higher loan amount may seem attractive, but it also means higher repayment obligations. Before applying, create a simple estimate: Required Amount = Actual Financial Requirement + Necessary Additional Costs Try to avoid unnecessary borrowing. For example, if your requirement is ₹5 lakh, taking a loan of ₹8 lakh simply because you are eligible for it may increase your financial burden without providing any real benefit. Borrowing should be based on need, affordability, and repayment ability. 3. Understand Your Repayment Capacity Before taking any loan, look at your current financial position. Consider: Your monthly loan repayment should fit comfortably within your budget. A loan may appear affordable when you look only at the EMI, but you should also consider the total financial commitment over the entire loan tenure. A responsible borrowing decision is one where the repayment remains manageable even when unexpected expenses arise. 4. Compare Interest Rates Carefully Interest rate is one of the most important factors when comparing loans—but it should not be the only factor. Borrowers should understand whether the interest rate is: It’s also important to compare the overall cost of borrowing, not just the advertised interest rate. Two loans may have similar interest rates but different processing fees, documentation charges, insurance requirements, or other costs. Always look at the complete financial picture before making a decision. 5. Choose a Loan Tenure That Fits Your Budget Loan tenure affects both your EMI and the total amount you pay over time. Generally: Shorter tenure → Higher EMI → Lower total interest Longer tenure → Lower EMI → Higher total interest A shorter tenure may help reduce the overall interest cost, but the higher EMI may put pressure on your monthly budget. A longer tenure may make repayments more manageable, but the total cost of borrowing can increase. The right tenure balances monthly affordability with the overall cost of the loan. 💡 A Simple Rule to Remember Don’t choose a loan only because the EMI looks affordable. Always consider: Loan Amount + Interest + Fees + Tenure + Your Repayment Capacity Together, these factors give you a more realistic understanding of whether a loan is suitable for you. 6. Understand the Difference Between Secured and Unsecured Loans One of the important factors to consider when choosing a loan is whether it is secured or unsecured. Secured Loans A secured loan is generally backed by an asset or collateral. Depending on the type of loan, this could involve property or another eligible asset. Because the loan is secured against an asset, the terms and eligibility criteria may differ from unsecured borrowing. Examples can include: Unsecured Loans Unsecured loans do not typically require the borrower to provide an asset as collateral. However, eligibility may depend more heavily on factors such as income, credit profile, repayment history, and other financial criteria. Personal loans are a common example of unsecured borrowing. The right option depends on your financial requirements, eligibility, and ability to meet the repayment terms. 7. Check Your Loan Eligibility Before Applying Before applying for a loan, it’s important to understand whether you meet the eligibility requirements. Lenders may consider factors such as: Eligibility criteria can vary between lenders and loan products. Understanding your eligibility beforehand can help you approach suitable options and avoid unnecessary applications.

Professional financial consultation in tesphero office
Finserv

Cashless vs Reimbursement Health Insurance Claims: What’s the Difference and Which One Is Better?

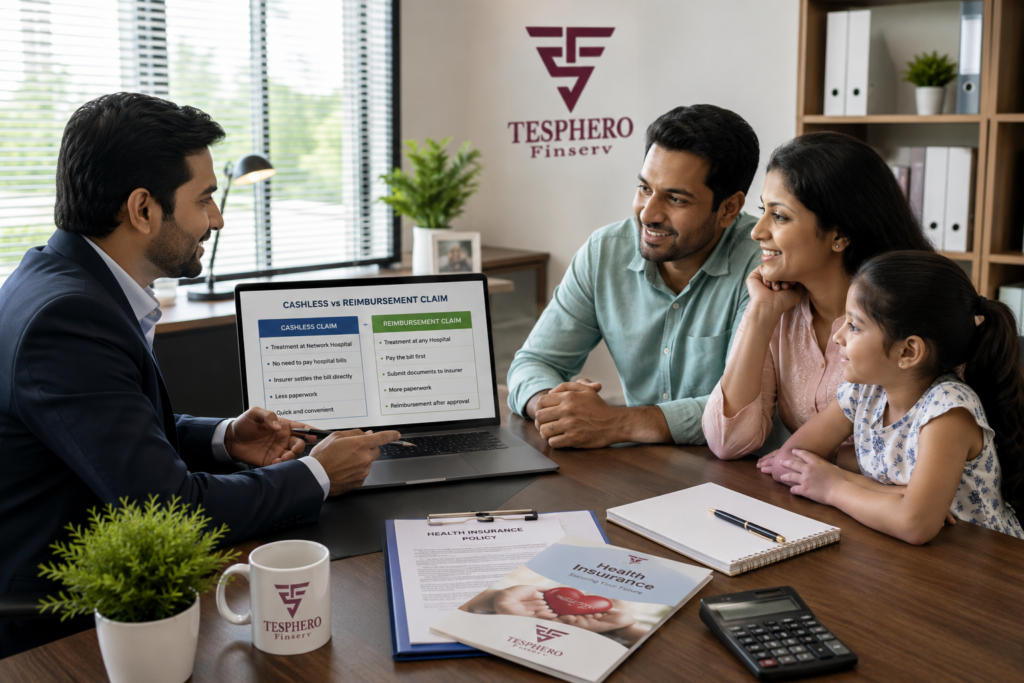
cashless-vs-reimbursement-health-insurance-claims Buying a health insurance policy is only the first step toward protecting yourself and your family. What truly matters is understanding how your policy works when you actually need to make a claim. One of the most common questions policyholders ask is: “Should I choose cashless treatment or reimbursement?” Many people assume both claim options are the same because, in the end, the insurance company pays for the treatment. However, the claim process, documentation, timelines, and overall experience can be very different. Imagine you’re admitted to a hospital in an emergency. The last thing you want is to worry about arranging a large amount of money or dealing with paperwork while your loved one is receiving treatment. Understanding the difference between cashless and reimbursement health insurance claims can help you make better decisions before an emergency occurs. In this guide, we’ll explain both claim methods in simple language, discuss their advantages and limitations, and help you understand which option may suit your needs. Table of Contents What Is a Health Insurance Claim? A health insurance claim is the process of requesting your insurance company to cover eligible medical expenses as per the terms of your policy. Depending on the hospital and your insurance provider, the claim is usually settled in one of two ways: Both methods are valid, but knowing when and how each one works can save you time, money, and unnecessary stress. What Is a Cashless Health Insurance Claim? A cashless claim allows policyholders to receive treatment at a network hospital without paying the full hospital bill upfront. Once your claim is approved, the insurance company settles the eligible expenses directly with the hospital. You may only need to pay for non-covered items, deductibles, or co-payments if applicable. How a Cashless Claim Works Benefits of Cashless Claims Things to Remember About Cashless Claims Although cashless claims are convenient, they are available only at your insurer’s cashless network hospitals. It’s also important to understand that not every medical expense is covered. Certain consumables, exclusions, co-payments, deductibles, or treatments outside your policy terms may still need to be paid by the policyholder. For this reason, checking your insurer’s network hospital list and understanding your policy benefits before an emergency can make the claim process much smoother. What Is a Reimbursement Health Insurance Claim? A reimbursement claim is used when you receive treatment at a hospital where the cashless facility is unavailable or when a cashless request cannot be processed. In this case, you pay the hospital expenses first and later submit the required documents to your insurance company for reimbursement. Once the insurer reviews your claim and verifies that the expenses are covered under your policy, the approved amount is transferred to your registered bank account. Although this process may take a little longer than a cashless claim, it provides flexibility by allowing you to choose treatment at hospitals outside the insurer’s network. How a Reimbursement Claim Works Benefits of Reimbursement Claims Cashless vs Reimbursement Health Insurance Claims Both claim options serve the same purpose—helping policyholders manage medical expenses—but the process is different. The table below compares cashless and reimbursement claims to help you understand the key differences at a glance. Feature Cashless Claim Reimbursement Claim Hospital Type Network Hospital Any Eligible Hospital Payment at Hospital The insurance company pays eligible expenses directly Policyholder pays first Claim Settlement During hospitalisation After discharge Documentation Minimal at the hospital Original bills and supporting documents required Financial Burden Lower Higher initially Best For Planned treatments and emergencies at network hospitals Hospitals outside the insurer’s network Expert Tip: Before a medical emergency, always check whether your preferred hospital is part of your insurer’s cashless network. This simple step can save valuable time during hospital admission. Which Claim Option Is Better? There isn’t a single answer because the right option depends on the situation. If you’re admitted to a network hospital, a cashless claim is usually the more convenient choice. It reduces immediate financial pressure and simplifies the billing process. However, if you receive treatment at a hospital outside your insurer’s network, a reimbursement claim allows you to recover eligible medical expenses after submitting the necessary documents. Instead of choosing one over the other, it’s more important to understand how both options work. Being aware of the claim process before an emergency can help you avoid unnecessary stress and delays. Common Mistakes That Delay Health Insurance Claims Many claim delays happen because important details are overlooked. A little preparation can make the entire process much smoother. Avoid these common mistakes: Taking a few minutes to review your policy and keep your documents organised can make a significant difference when you need to file a claim. 🤝 How Tesphero Finserv Helps You Choose the Right Health Insurance Health insurance isn’t just about comparing premiums. The right policy should match your healthcare needs, family size, budget, and future financial goals. At Tesphero Finserv, we understand that every family has different priorities. That’s why we focus on helping clients make informed decisions instead of simply recommending a policy. With 10+ years of experience in the financial services industry, we’ve helped individuals, families, and business owners choose suitable health insurance plans while providing guidance throughout the claim process. Our Health Insurance Services Include: Our goal is simple—to help you protect your family’s health while making the insurance process easy to understand. Cashless claims are generally more convenient at network hospitals, while reimbursement claims provide flexibility when treatment is received elsewhere. Understanding both options before a medical emergency helps you make informed healthcare and financial decisions. 💡 Final Thoughts Medical emergencies can happen without warning, but financial stress doesn’t have to follow. Understanding the difference between cashless and reimbursement health insurance claims helps you make better decisions before you actually need to use your policy. A cashless claim can reduce immediate financial pressure when treatment is taken at a network hospital, while a reimbursement claim offers flexibility when treatment is received elsewhere. Both options are valuable when you

Finserv

10 Things You Must Check Before Buying a Health Insurance Policy in India

Home > Health Insurance > Buying Guide Don’t buy a health insurance policy just because it looks affordable. Here’s a practical guide to help you make a smarter and more informed decision. Introduction Medical expenses in India have increased significantly over the past few years. A single hospitalization can cost anywhere from ₹2 lakh to ₹10 lakh, depending on the treatment, hospital, and city. While many people understand the importance of health insurance, choosing the wrong policy can leave you with unexpected out-of-pocket expenses when you need financial support the most. Today, there are hundreds of insurance plans available, each offering different features, benefits, exclusions, and claim conditions. A lower premium may seem attractive initially, but it doesn’t always provide the protection you and your family actually need. Whether you’re buying your first health insurance policy, upgrading your existing coverage, or planning to purchase a mediclaim policy online, understanding the key factors before making a decision can save you from costly surprises later. This guide covers the 10 most important things to check before buying a health insurance policy in India, helping you choose coverage that provides real financial security—not just a policy document. “The best time to buy health insurance isn’t when you’re sick—it’s when you’re healthy.” Table of Contents 1. Choose the Right Sum Insured The first decision is selecting an adequate sum insured. Medical inflation in India continues to rise, making small coverage amounts insufficient for many families. For example, a major surgery in a private hospital can easily exceed ₹5 lakh. If your policy covers only ₹3 lakh, you’ll have to pay the remaining amount yourself. When deciding your coverage, consider: Many financial advisors recommend choosing at least ₹10–20 lakh coverage for urban families. 2. Check the Waiting Period Most policies don’t cover every illness immediately after purchase. Always review the waiting periods for: Understanding these conditions helps avoid claim rejections during the initial years of your policy. 3. Understand Coverage for Pre-Existing Diseases If you or a family member has diabetes, hypertension, thyroid issues, asthma, or any existing medical condition, carefully check the pre-existing diseases cover. Different insurers have different waiting periods, usually ranging from 2 to 4 years. Ask yourself: Buying the right policy early helps reduce future risks. 4. Check the Cashless Network Hospitals One of the biggest advantages of modern health insurance is access to cashless network hospitals. Instead of arranging large sums during emergencies, eligible treatments can be settled directly between the insurer and the hospital. Before purchasing a policy: A large network improves convenience during medical emergencies. 5. Check the Room Rent Limit Many buyers overlook room rent limits until they file a claim. Some policies allow only a fixed room category or cap the room rent at a certain percentage of the sum insured. Choosing a room above the permitted limit may increase your overall bill because several hospital charges are linked to the room category. Always check whether your policy offers: A policy with flexible room rent benefits can significantly reduce unexpected expenses. 6. Understand the Co-Payment Clause A co-payment clause means you’ll bear a fixed percentage of every claim while the insurer pays the remaining amount. For example: If your hospital bill is ₹5 lakh and your policy has a 20% co-payment, you’ll pay ₹1 lakh from your own pocket. Before buying, understand: For younger policyholders, plans without co-payments are often preferred. 7. Review Daycare Treatment Coverage Modern healthcare has advanced considerably. Many treatments no longer require 24-hour hospitalization. These are called daycare treatments. Examples include: A good health insurance policy should cover a wide range of daycare procedures without requiring overnight admission. 8. Check the Restoration Benefit One hospitalization can completely exhaust your sum insured. That’s where the restoration benefit becomes valuable. If your coverage is fully utilized during one claim, restoration benefits automatically reinstate your insured amount for eligible future claims within the same policy year. This feature is especially useful for: Always check how and when restoration applies. 9. Understand the No Claim Bonus A no-claim bonus in a health insurance rewards policyholders for not making claims during a policy year. Instead of cash rewards, insurers usually increase your sum insured without increasing the premium proportionately. For example: Over time, this bonus can substantially enhance your financial protection. Always review: 10. Compare the Health Insurance Claim Settlement Ratio The health insurance claim settlement ratio indicates the percentage of claims settled by an insurance company. Although it shouldn’t be the only deciding factor, it provides useful insight into an insurer’s claim-handling performance. While comparing insurers, also consider: Choosing the best health insurance in India involves balancing all these factors—not just selecting the cheapest premium. Quick Health Insurance Policy Checklist Before buying any health insurance policy, compare these features instead of choosing a plan based only on the premium. A slightly higher premium can often provide significantly better coverage and long-term financial protection. Feature What You Should Check Why It Matters Sum Insured ₹10–20 lakh or higher (based on your needs) Covers rising medical expenses Pre-Existing Diseases Cover Waiting period and covered illnesses Avoids claim surprises later Room Rent Limit No cap or Single Private Room Prevents additional out-of-pocket expenses Co-Payment Clause Prefer lower or no co-payment Reduces your share of hospital bills Cashless Network Hospitals Hospitals available near your location Ensures hassle-free treatment during emergencies Daycare Treatments Wide range of covered procedures Covers treatments without 24-hour hospitalization Restoration Benefit Automatic restoration of sum insured Helpful for multiple claims in one year No Claim Bonus Bonus percentage and maximum limit Increases your coverage over time Claim Settlement Ratio Compare the insurer’s recent performance Indicates claim handling efficiency Health Insurance Comparison at a Glance Final Thoughts Buying health insurance is one of the most important financial decisions you’ll make for yourself and your family. The right policy should provide peace of mind, not confusion at the time of a medical emergency. Instead of focusing only on premium costs, compare the overall benefits, coverage, exclusions, hospital network,

Scroll to Top